G’day Paul,
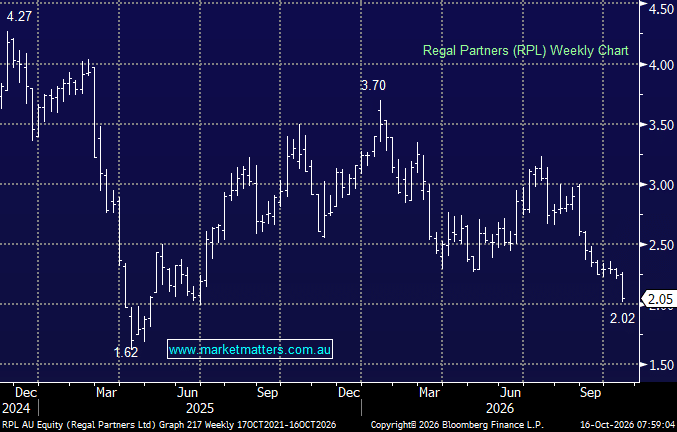
Regal (RPL) looks a bit buggered at the moment! The share price continues to slide, even on good days in the market, which is never a particularly encouraging sign.
We wrote about it here when it was trading around $2.40, and fundamentally, not a great deal has changed, although the failed listing of Firmus, in which Regal has a significant investment, has added another layer of uncertainty.
We still regard Regal as a good business, but the market seems increasingly concerned about two things: 1. Phil King’s planned retirement, as you mentioned, and 2. the recent weak performance of some of its equity strategies, covered in another question.
In our world, Regal has historically demonstrated a genuine edge, with strong investment performance justifying its higher-fee approach. However, performance has recently struggled, and as we’ve seen with other listed active managers, (eg MFG and GQG), sustained underperformance can lead to fund outflows.
That hasn’t become a major issue for Regal at this stage, but it is certainly the risk. Further complicating matters is the potential for fee compression and lower performance fees, both of which can have a disproportionate impact on profitability. Fund management businesses have significant operating leverage, and with the continued rise of passive investing, active managers need to consistently add value or risk losing clients to cheaper alternatives.
Phil King’s departure is particularly relevant because he has been instrumental in building Regal’s reputation and investment culture. While the transition is being managed over an extended period, the market is understandably questioning whether the business can maintain its historical investment performance without him at the helm.
For now, RPL looks undervalued, trading on ~7x earnings, although the market is clearly questioning how sustainable those earnings will be. We suspect Regal could also be on the radar of other asset managers, with L1 Group springing to mind, particularly given its scrip trades on a significantly higher multiple of around 20x earnings.
We still like Regal, just not its share price! We believe there is value at current levels, but if we didn’t already hold a position, we’d prefer to see some stabilisation in the share price, and ideally signs of improving investment performance, before stepping up and buying. We’re not throwing in the towel, but neither are we rushing to add to our position.
Premier Investments (PMV), this is currently featured in Shawn’s Trade Ideas section of the website here.
Following a significant restructuring, Premier is now a much simpler business, focused on two retail brands, Peter Alexander and Smiggle, alongside its substantial investment in Breville (BRG). We understand your concern about the disposal of its other retail brands, but we actually view the simplification as a positive. The brands transferred to Myer were generally more mature, lower-growth businesses, while Peter Alexander has been Premier’s standout performer for many years. The restructuring allows management to concentrate capital and resources on the businesses with the greatest potential to grow sales, earnings and margins.
Peter Alexander remains the jewel in the crown where as Smiggle is more of a turnaround story. Importantly, Premier also has a very strong balance sheet. At the end of FY26, it held approximately $390m in cash, alongside a 25.2% stake in Breville worth around $1.08bn at the time. These are significant assets that underpin the company’s valuation and provide considerable flexibility. Our view remains positive, and we still regard PMV as a Buy at current levels.