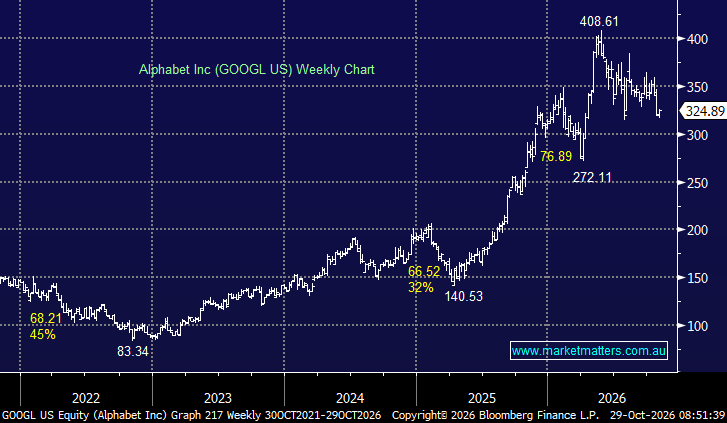
Alphabet (GOOGL) reported after the close and was trading around 9% lower after hours, with the market focusing on softer Search and advertising trends, weaker margins and the scale of AI-related capital spending despite another exceptional quarter from Google Cloud.
Key Q3 highlights:
- Revenue: US$127.58bn, up 25% YoY vs US$127.93bn expected.
- Revenue ex-TAC: US$111.21bn vs US$111.29bn expected.
- Google Search revenue: US$63.35bn vs US$64.85bn expected.
- Google advertising revenue: US$82.01bn vs US$83.57bn expected.
- Google Cloud revenue: US$30.71bn, more than doubling YoY vs US$29.1bn expected.
- Operating margin: 32% vs 33.7% expected.
- Capex: US$51.36bn, more than double YoY.
- Free cash flow: negative US$9.1bn
Cloud was outstanding, with enterprise AI demand remaining very strong. The concern is that the core Search franchise is showing signs of pressure at the same time Alphabet is spending aggressively to extend its position in AI. That tension is now central to the investment case. AI is creating a major new growth engine through Cloud, but it is also increasing capital intensity and potentially disrupting the economics of Search. In simple terms, Google could end up cannibalising its own Search business as users increasingly turn to AI for answers rather than traditional search results.
MM’s view: The Cloud result was a clear positive, highlighting strong enterprise AI demand and Alphabet’s ability to monetise its infrastructure. However, we remain cautious on the stock, with the key question being whether Cloud growth can justify the significant ramp-up in capital expenditure, particularly as AI threatens to disrupt the core Search business that has historically underpinned the group’s earnings and cash flow.
MM is neutral toward GOOGL ~$US320
Add To Hit List