The ASX has been rife with takover interest in recent weeks, and we think ABB is an another increasingly attractive takeover candidate, with its growing scale, recurring revenues and improving earnings profile making it a logical target for both private equity and larger telecommunications players.
ABB has evolved well beyond a residential broadband provider, building a diversified telecommunications business spanning residential, enterprise and wholesale customers. With more than 1.1 million broadband connections, around 12% NBN market share and a growing network infrastructure footprint, acquiring ABB would provide immediate scale in a market where organic growth is increasingly difficult.
Importantly, earnings momentum is strong. FY26 underlying earnings (EBITDA) increased 19.6% to $165.3m, with FY27 guidance of $205–215m implying another 24–30% growth. This combination of recurring revenue, operating leverage and improving cash generation would be particularly attractive to private equity, while strategic acquirers could potentially extract meaningful cost synergies through network, technology and operational consolidation.
Who might be interested? Private equity is probably the most logical buyer, while TPG Telecom (TPG) and Superloop (SLC) offer intersting industrial combinations. ABB previously attempted to acquire Superloop in 2024, highlighting the strategic rationale for consolidation between the two businesses. Vocus is another potential suitor, while Telstra and Optus would likely face regulatory hurdles.
One complication is ABB’s recently established partnership with AGL Energy (AGL), which now owns around 7% of the company following the sale of its telecommunications business to ABB. The agreement effectively prevents AGL from supporting or voting in favour of a third-party takeover unless it is recommended by ABB’s board. AGL is also restricted from launching its own takeover without prior board support. These provisions don’t prevent a takeover, but they provide ABB’s board with an additional layer of protection against an unsolicited approach. The agreement also gives AGL certain termination rights following a change of control, something a potential acquirer would need to consider.
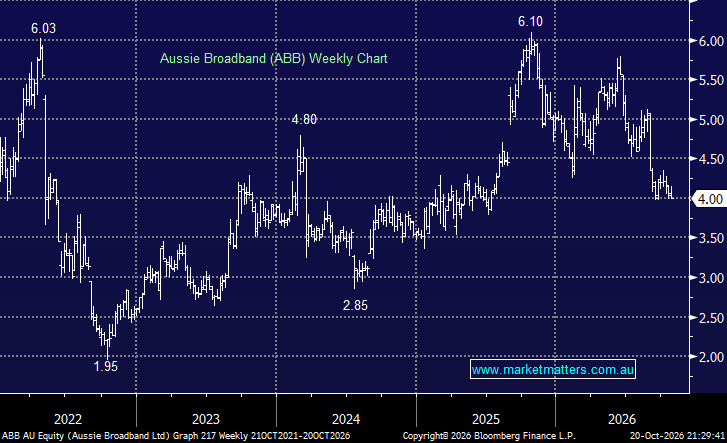
At ~$4.00 per share, down from recent highs of ~$5.80, ABB has an equity value of ~$1.26bn, making it a digestible acquisition for a well-capitalised buyer. A conventional 25–35% takeover premium would imply a price of $5.00–5.40, although any bidder would need to factor in ABB’s accelerating earnings growth.
As we often say at MM, takeovers are not the reason to own a stock, but they are interesting to think about when the standalone investment thesis still stacks up, as we think it does with ABB. Ultimately, we see a credible takeover argument for ABB, particularly given its expanding market position, strong earnings momentum, potential synergies for an acquirer, and depressed share price.
MM remains long & bullish ABB
Add To Hit List