Hi Darren,
Our investment thesis on Applied Materials (AMAT) remains intact following its Investor Day, and we continue to like the stock at current levels. While the market was clearly disappointed by the lack of specific financial guidance, we don’t believe anything presented materially undermines the longer-term growth opportunity.
The key points from the Investor Day were broadly positive:
- Industry growth: Management expects wafer fabrication equipment (WFE) spending to grow faster through 2030 than it did over the previous decade, supported by AI infrastructure investment and increasingly complex semiconductor manufacturing.
- Market share: AMAT is targeting a 2-percentage-point increase in market share between 2025 and 2030, which should allow it to grow faster than the broader semiconductor equipment market.
- Profitability: The company is targeting gross margins of around 54% and operating margins of approximately 40%, suggesting meaningful operating leverage as revenue expands.
- Earnings potential: We estimate the industry could grow ~20% annually through 2030, with AMAT potentially growing faster, supporting earnings of US$25–30 per share by the end of the decade.
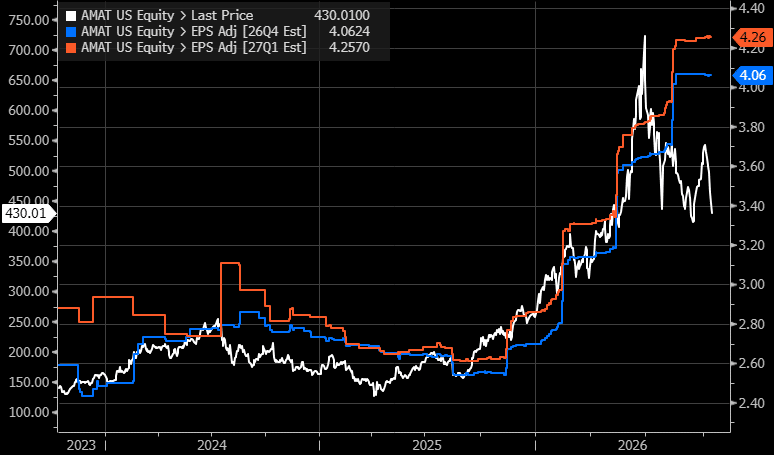
The disappointment was that management stopped short of providing specific revenue or WFE spending forecasts, claiming uncertainties around factory capacity, supply chains and financing. While we understand the market’s reaction, we haven’t seen analysts materially downgrade their earnings expectations following the event, which is encouraging. The below chart shows consensus EPS forecasts remaining solid i.e. no material downgrades post this update. This suggests the recent weakness is more about expectations, positioning and valuation than a deterioration in the underlying earnings outlook.
We remain constructive on the semiconductor equipment industry over the medium term, particularly AMAT’s exposure to advanced logic, DRAM and high-bandwidth memory, where increasing manufacturing complexity should support equipment spending. However, this is a volatile stock, in a volatile sector that has been hit hard this week – hence our 4% target weighting, and if the equity market rally broadens, it’s a stock that could take some time to recover.