Hi Rob,
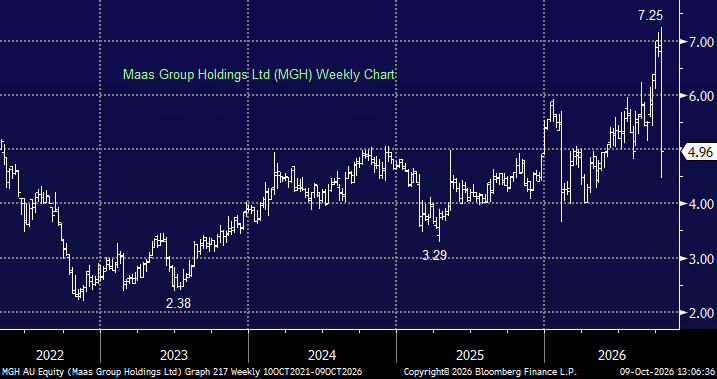
MGH had a tough week after AI data centre developer Firmus was forced to shelve its IPO due to insufficient investor demand. MGH owns 3.2% of Firmus, and the market had been valuing this stake based on the implied ~$44bn valuation associated with the proposed $11 per share listing price. That valuation was subsequently revised lower, but the IPO still failed to attract enough buying interest and was ultimately withdrawn. Firmus is now looking to raise capital privately, although we expect both the size of the raise and the valuation to be materially below those initially targeted for the IPO. Firmus’s last private funding round in August 2026 raised US$2bn at a valuation of ~US$10.5bn, highlighting just how ambitious the proposed $5.5bn IPO raise at a $44bn valuation was.
However, the bigger issue for MGH isn’t its equity stake in Firmus, but rather the implications for its substantial electrical infrastructure order book if Firmus fails to secure additional equity funding. Following the $1.61bn sale of its construction materials division to Heidelberg Materials, MGH has repositioned itself towards electrical and digital infrastructure, and it has put plenty of eggs in the Firmus basket. A well-capitalised Firmus would have been a major positive for MGH, but with its funding position now less certain, MGH’s outlook has weakened. The substantial long-term contracts secured by its electrical infrastructure division to supply modular power equipment now carry greater execution risk, particularly if Firmus is unable to secure the capital required to fund its ambitious development pipeline.
Firmus has bold and aggressive plans for data centre development, but delivering on those ambitions requires enormous amounts of capital. A successful listing would have materially strengthened its balance sheet and funding capacity, accelerating its ability to execute on its growth plans. The failed IPO raises questions about the timing and scale of future developments, which could have direct implications for MGH’s earnings growth. This uncertainty helps explain the sharp sell-off in MGH shares.
We believe the failed Firmus IPO is a significant negative for MGH, but the extent of the damage remains unclear. Much will depend on Firmus’s ability to secure alternative funding, the valuation achieved and whether its development timetable needs to be revised. Until there is greater clarity around its next equity raising, we expect uncertainty to weigh on MGH shares.