Hi Simon,
Fortescue (FMG) has significantly scaled back its ambitious global green hydrogen strategy, but it hasn’t abandoned its broader decarbonisation plans. The company has scrapped its Arizona hydrogen project and Gladstone’s PEM50 development, effectively shelved its proposed ~$3bn Brazilian hydrogen and ammonia project, and substantially reduced the operations of its New York-based Fortescue Capital business.
These decisions reflect the challenging economics of green hydrogen, shifting government policies and a renewed focus on capital discipline, with management increasingly reluctant to commit billions to projects without a clear commercial pathway.
Importantly, Fortescue remains committed to eliminating Scope 1 and 2 emissions from its Australian iron ore operations by 2030, with its ~$6.2bn Pilbara decarbonisation program approximately 24% complete at June 2026.
- The company invested around US$848m in renewable energy, battery storage and transmission infrastructure during FY26, with a further US$900m–1.3bn earmarked for FY27.
- It is also developing a broader Pilbara green energy hub, including an additional US$680m investment in infrastructure potentially available to third parties, while continuing research into green hydrogen and green metals technology.
Fortescue’s green ambitions have become considerably more pragmatic, shifting away from speculative global hydrogen projects towards initiatives that directly benefit its core iron ore operations. However, the commercial rationale is compelling; electrification and renewable energy could reduce operating costs by US$2–4 per tonne by 2030 through lower diesel and gas consumption.
While execution risks remain, we view the renewed emphasis on capital discipline positively. Fortescue hasn’t abandoned its green strategy – it has narrowed its focus to projects with a clearer pathway to generating shareholder returns.
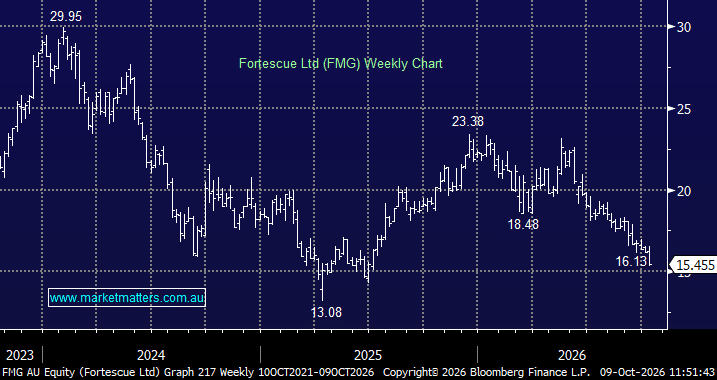
Hence at this stage from an earnings perspective FMG is an iron ore miner with several issues weighing on the share price:
- Lower iron ore prices: Consensus forecasts iron ore falling from ~US$100/t in FY26 to US$95/t in FY27 and US$89/t in FY28.
- Weak Chinese demand and contract uncertainty: China’s struggling property sector and softer steel demand remain structural headwinds.
- Higher capital expenditure: Capex is forecast to rise from US$3.2bn in FY26 to ~US$4.4bn in FY27, driven by Pilbara decarbonisation, mine development and infrastructure spending.
- Rising operating costs: Higher hematite costs and delays at Iron Bridge are squeezing margins, although costs and capex should moderate from FY28.