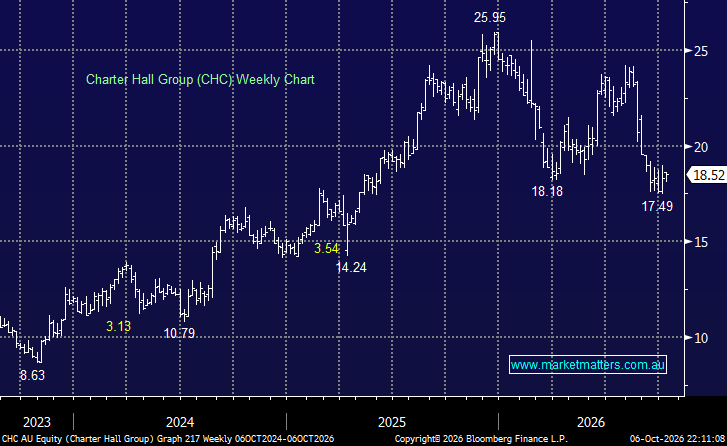
Property has been firmly on the nose as bond yields have pushed higher, and Charter Hall (CHC) has been hit particularly hard. The stock has fallen sharply since August as investors price in lower property values, softer transaction activity and pressure on earnings. We think the market may be getting too bearish.
CHC is not simply a property owner – it is one of Australia’s largest property fund managers, with earnings generated across funds management, property investment and development. Importantly, FY27 operating EPS is still expected to grow at around 10-13%, despite the tougher rate backdrop.
The key issue is interest rates. CHC has historically been one of the most rate-sensitive large-cap property names, tending to underperform when bond yields rise and outperform when they fall. That has been a major driver of the recent weakness. However, we think this cycle is different to 2022-23. Back then, CHC faced both a sharp multiple contraction and falling earnings, with unusually high performance fees rolling out of the earnings base. Today, earnings quality is cleaner, property values have already been materially written down, and transaction activity is starting from a much lower base. Income is growing, even if the headline yield is modest
CHC is not a traditional high-yield property stock. FY26 distributions were 50.7c per share against operating EPS of 103.2c, implying a payout ratio of just under 50%. UBS expects distributions to rise to 53.7c in FY27, 56.9c in FY28 and 60.3c in FY29, while the payout ratio falls toward the low-40% range.
At current levels, the forward yield is only around 3%, but we see CHC more as an income growth stock than a high-yield REIT. The conservative payout ratio provides room for distributions to grow alongside earnings.
Valuation is where the story gets more compelling. At $18.50, CHC is trading on around 15x FY27 earnings, falling to 14x in FY28 and 12.5x in FY29. At the same time, FY27 EPS growth is forecast at around 13%, comfortably above the broader market. CHC is also trading at a significant discount to its historical relative valuation, with its P/E relativity to the ASX 200 close to levels seen around previous troughs.
While CHC is not an obvious Income Portfolio stock based on yield alone, we like the combination of growing distributions, a conservative payout ratio, double-digit earnings growth and a heavily compressed valuation.
Property may remain under pressure while bond yields are rising, but if we apply a +12-month view, the setup is becoming increasingly attractive. We don’t need rates to collapse; simply stabilising bond yields should be enough to remove one of the major valuation headwinds.
- MM is adding CHC to our Income Portfolio Hitlist. We are not chasing the stock immediately given our existing property exposure in Mirvac (ASX: MGR) & Charter Hall Long WALE REIT (ASX: CLW), but we do believe the risk/reward is becoming compelling around current levels for those investors with a greater focus on growth than pure income alone.
MM is bullish CHC ~$18.50
Add To Hit List