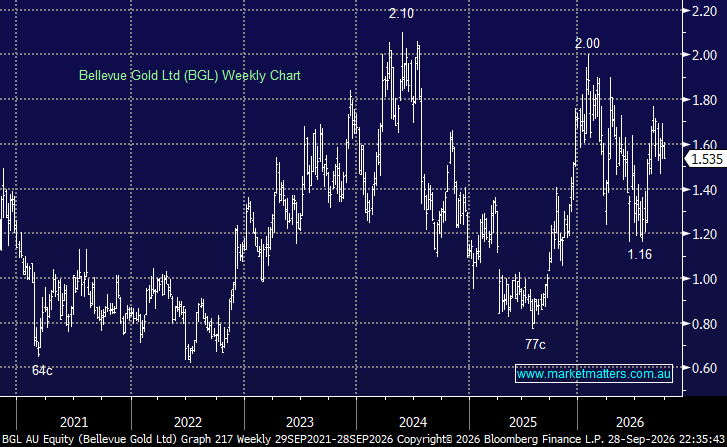
Bellevue Gold (BGL) has emerged from its difficult 2025 in far better shape, with FY26 production of 143.5koz in the upper half of guidance, cash and gold reaching $206m and forward sales commitments cut by 55%. However, it remains a relatively small, single-asset producer in WA’s northern Goldfields, with high All-In-Sustaining-Cost (AISC) of $2,600–2,900/oz and a valuation still carrying the scars of its operational problems. That combination makes Bellevue relatively straightforward for a larger miner to absorb, particularly one looking to build scale in the region.
Importantly, the M&A angle is more than theoretical. Bellevue explored takeover interest in 2025, with Regis, Agnico Eagle, United Tractors and Vault reportedly among the interested parties, while more recent speculation has included a potential combination with Catalyst Metals. Its register also looks relatively open, with BlackRock recently lifting its holding to 14%, Fourth Sail Capital holding almost 9% and limited board ownership. With the turnaround gaining traction, Bellevue arguably becomes a more attractive target as operational risk falls—but it still needs to prove it can deliver consistently.
Gold Fields arguably offers the cleanest strategic fit, with Agnew directly adjacent to Bellevue’s southern boundary, making BGL a natural bolt-on to its existing WA operations. Northern Star has the broader regional footprint, with several nearby mines and processing infrastructure that could potentially accommodate Bellevue’s high-grade ore, similar to the regional consolidation logic behind Genesis and Vault.
If Gold Fields fails to secure Northern Star, Bellevue could offer a far cheaper and more manageable alternative, adding high-grade WA production in a district where it already operates and understands the geology.
- We believe BGL is likely to be acquired moving forward. We own the miner in our Emerging Companies Portfolio.
MM is cautiously bullish towards gold
Add To Hit List