Origin Energy (ORG) delivered a solid FY26 result in August, with underlying earnings (NPAT) 3% ahead of consensus, while FY27 guidance for Energy Markets was around 5.5% above expectations at the midpoint. New battery earnings are expected to offset much of the impact from softer near-term wholesale electricity prices while ORG’s overall cost base has been well managed in recent years which gives them a good platform to work with from here.
- Importantly, electricity and gas prices are around cyclical lows, with risks arguably skewed to the upside as data-centre (DC) demand grows, NSW smelters remain operational and thermal generation capacity is retired from 2028.
ORG exited FY26 in a strong position, with $911m of net cash distributions from APLNG helping reduce adjusted net debt/EBITDA down to 1.6x, well below its 2–3x target range, while FY27 capex guidance of $450–650m was also comfortably below consensus of $712m. Against this backdrop, the 30c final dividend looked conservative, suggesting management may be retaining firepower for growth.
There is no shortage of potential opportunities for ORG, including further acquisitions of smaller energy and broadband retailers, expanding the Kraken platform, additional investment in Octopus Energy/Kraken and providing large-scale energy solutions to DCs and hyperscalers. At the same time, FY27 Energy Markets earnings (EBITDA) guidance was more than 5% above consensus – a strong outcome with electricity prices around cyclical lows despite more than 20GW of coal generation expected to retire and significant additional demand forecast from electrification, EVs and data centres.
- ORG’s combination of balance-sheet strength, resilient earnings and multiple growth options leaves it well placed to both invest and increase shareholder returns moving forward.
In terms of growth, the demand for electricity is increasing as data centres (DCs), EVs and industrial electrification increasingly outweigh the demand suppression from rooftop solar, with DCs emerging as the most significant incremental load driver into the 2030s.
- DCs are the standout growth driver: Australian Energy Market Operator (AEMO) expects electricity consumption from DCs to rise almost seven-fold by 2035-36, increasing their share of National Electricity Market (NEM) demand from roughly 3% to 13%.
- EV adoption provides another structural tailwind: Electricity consumed by EVs is expected to steadily increase as penetration rises, adding another significant source of demand through the remainder of the decade.
- Industrial electrification should add further load: Green hydrogen, green steel, aluminium smelting and the broader replacement of fossil fuels with electricity could materially increase industrial power requirements, particularly from the late 2020s.
- Rooftop solar remains the major offset: Continued growth in behind-the-meter solar and batteries will suppress grid demand during daylight hours, partially offsetting these new sources of consumption. However, the overall balance is increasingly shifting towards net demand growth, with data centres expected to become the dominant incremental driver.
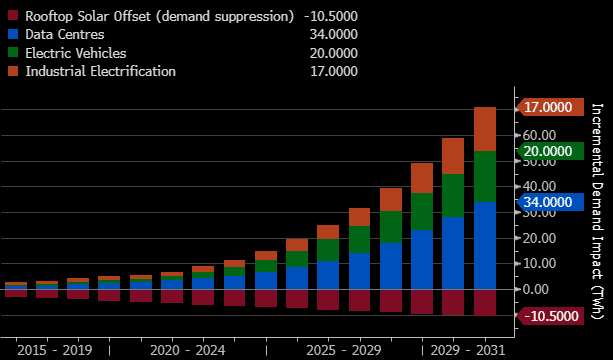
chart

Australia NEM: Incremental Electricity Demand Drivers (TWh) – Estimate: Source: Bloomberg
chart
Australia NEM: Incremental Electricity Demand Drivers (TWh) – Estimate: Source: Bloomberg
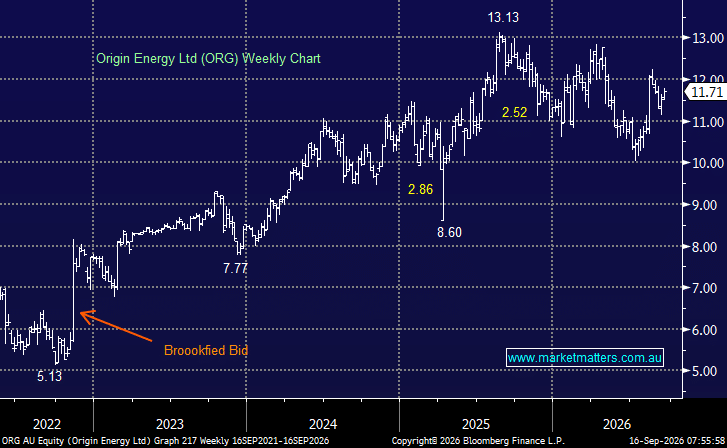
The Brookfield bid in late 2022 was an important event for ORG, refocussing the markets attention on the embedded value and removing much of the valuation discount the stock had previously held. Subsequent strong earnings cycles (particularly FY24’s near-zero to A$747M 1H profit swing) validated the higher valuation, keeping the PE elevated even as the takeover ultimately did not proceed.
- After we took profit on our APA position in June here ORG is becoming an attractive option for new utilities exposure.
Adding further spice to the ORG story, Utilities were the ASX 200’s best-performing sector in 2H22, rallying 27%, an interesting historical parallel given the similarities MM has been drawing between 2022 and 2026 in recent weeks.
- We can see ORG punching to new highs into 2027, around 15% upside plus a nice fully franked yield along the way – we have added ORG to our Hitlist.
MM is positive on ORG below $12
Add To Hit List