Bond markets and central banks are back in focus after Friday night's August US jobs report came in far stronger than expected, with nonfarm payrolls rising by 162,000—more than triple consensus forecasts—while unemployment held steady at 4.1%. Labour-force participation also improved, and prior months were revised higher, reinforcing signs that the jobs market has rebounded from its early-summer softness, shifting attention firmly to this week’s CPI (inflation) data, with the resilient labour market increasing the prospect of a Fed rate hike at next week's meeting.
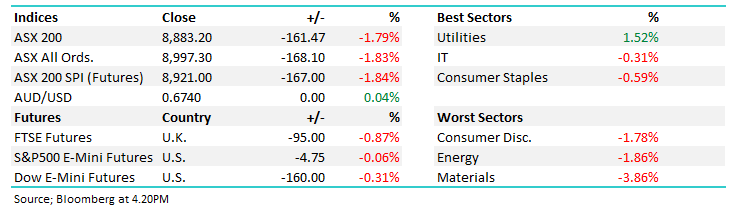
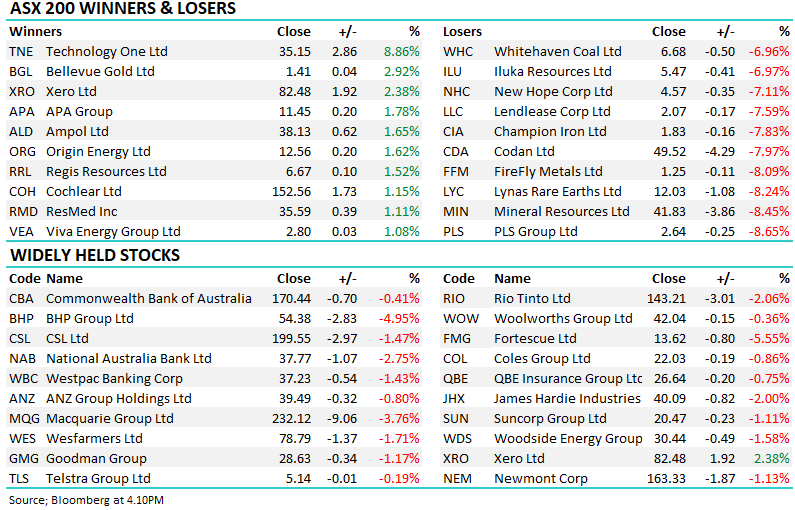
The ASX 200 bounced +0.5% on Thursday, regaining some of the previous session's steep losses as the heavyweight banks, ably supported by the miners, combined to lift the index, not a bad performance with BHP, Coles, Amco and Woodside all trading ex-dividend. To put the banks’ strength into perspective, the Big Four alone accounted for ~50% of the market’s advance on the day.
The ASX 200 was clobbered 1.0% on Wednesday as broad-based selling rolled through the local bourse as surging global bond yields continued to dominate the financial press. More than 70% of the main board retreated, with the tech (-3.4%) and materials (-3.1%) vying for the wooden spoon as risk-off sentiment was evident across the market - the defensive-oriented consumer staples (+0.8%) were not surprisingly the best-performing sector.
The ASX 200 bounced strongly from its early morning low on Tuesday, recovering ~80% of its initial drop to end the session down just -0.1%. A solid performance in our opinion, considering the negative lead from global bonds as oil prices continued to climb on renewed tensions in the Middle East.
The ASX 200 recovered impressively from an early sell-off to finish the final session of August down just -0.2%, a better outcome than we expected, with the Big Four banks adding around 30 points to the index. Interestingly, while resources retreated following Fed Chair Warsh’s hawkish comments on Friday and renewed tensions between the US and Iran, there was little evidence of broad-based selling.
Two weeks ago, Scott Bessent emerged as one of the most interventionist US Treasury secretaries in decades, in an attempt to stem the increasing burden of the rise in US borrowing costs.
The ASX 200 was clobbered on Thursday, as a trifecta of bad news overshadowed another impressive result from Nvidia. Selling was broad-based, with more than 75% of the main board leading the market's worst day since June. Globally, it was a session that favoured semiconductors over miners, an unfortunate combination for the local market given the ASX is heavily exposed to the latter and has virtually none of the former:
The ASX 200 surrendered early gains on Wednesday after inflation data came in far stronger than expected, weighing heavily on overall sentiment and specifically the rate-sensitive names. Just to compound the market’s woes, yesterday's reporting wasn’t kind, with major disappointments from Worley (-10.8%), WiseTech (-10.1%), and Flight Centre (-7.4%) offsetting further strength in gold and copper names.
The ASX 200 enjoyed a more broad-based advance on Tuesday, with 70% of the main board closing higher, pushing the index up +0.7%. The banks finally gave the index a helping hand, but they still couldn’t figure in the top 3 stocks contributing to the market's 62-point advance; the podium was headed by BHP, again (+9 points), followed by CSL (+7-points), and Suncorp (+5-points). Elsewhere, we saw some profit-taking creep into the high-flying gold sector while the tech stocks more than picked up the slack, taking their cue from a reversal higher by the semiconductor-driven Korean KOSPI Index.
The ASX 200 rallied +0.5% on Monday to close just above the psychological 9100 level, but it wasn't all plain sailing with less than 55% of the main board closing higher. The story remained consistent on the sector front, with the gains by the materials (+61 points) minus the financials (-21 points) almost exactly equalling the day's +44-point net advance. The miners remain the driving force of the ASX, and the reason we’ve recently been outperforming the US, especially since the Treasury pledged support to try and rein in long-dated US bond yields. BHP Group (BHP) grabbed the headlines on Monday, posting new all-time highs, but there were plenty of standout performances amongst the big miners.
The ASX 200 bounced +0.5% on Thursday, regaining some of the previous session's steep losses as the heavyweight banks, ably supported by the miners, combined to lift the index, not a bad performance with BHP, Coles, Amco and Woodside all trading ex-dividend. To put the banks’ strength into perspective, the Big Four alone accounted for ~50% of the market’s advance on the day.
The ASX 200 was clobbered 1.0% on Wednesday as broad-based selling rolled through the local bourse as surging global bond yields continued to dominate the financial press. More than 70% of the main board retreated, with the tech (-3.4%) and materials (-3.1%) vying for the wooden spoon as risk-off sentiment was evident across the market - the defensive-oriented consumer staples (+0.8%) were not surprisingly the best-performing sector.
The ASX 200 bounced strongly from its early morning low on Tuesday, recovering ~80% of its initial drop to end the session down just -0.1%. A solid performance in our opinion, considering the negative lead from global bonds as oil prices continued to climb on renewed tensions in the Middle East.
The ASX 200 recovered impressively from an early sell-off to finish the final session of August down just -0.2%, a better outcome than we expected, with the Big Four banks adding around 30 points to the index. Interestingly, while resources retreated following Fed Chair Warsh’s hawkish comments on Friday and renewed tensions between the US and Iran, there was little evidence of broad-based selling.
Two weeks ago, Scott Bessent emerged as one of the most interventionist US Treasury secretaries in decades, in an attempt to stem the increasing burden of the rise in US borrowing costs.
The ASX 200 was clobbered on Thursday, as a trifecta of bad news overshadowed another impressive result from Nvidia. Selling was broad-based, with more than 75% of the main board leading the market's worst day since June. Globally, it was a session that favoured semiconductors over miners, an unfortunate combination for the local market given the ASX is heavily exposed to the latter and has virtually none of the former:
The ASX 200 surrendered early gains on Wednesday after inflation data came in far stronger than expected, weighing heavily on overall sentiment and specifically the rate-sensitive names. Just to compound the market’s woes, yesterday's reporting wasn’t kind, with major disappointments from Worley (-10.8%), WiseTech (-10.1%), and Flight Centre (-7.4%) offsetting further strength in gold and copper names.
The ASX 200 enjoyed a more broad-based advance on Tuesday, with 70% of the main board closing higher, pushing the index up +0.7%. The banks finally gave the index a helping hand, but they still couldn’t figure in the top 3 stocks contributing to the market's 62-point advance; the podium was headed by BHP, again (+9 points), followed by CSL (+7-points), and Suncorp (+5-points). Elsewhere, we saw some profit-taking creep into the high-flying gold sector while the tech stocks more than picked up the slack, taking their cue from a reversal higher by the semiconductor-driven Korean KOSPI Index.
The ASX 200 rallied +0.5% on Monday to close just above the psychological 9100 level, but it wasn't all plain sailing with less than 55% of the main board closing higher. The story remained consistent on the sector front, with the gains by the materials (+61 points) minus the financials (-21 points) almost exactly equalling the day's +44-point net advance. The miners remain the driving force of the ASX, and the reason we’ve recently been outperforming the US, especially since the Treasury pledged support to try and rein in long-dated US bond yields. BHP Group (BHP) grabbed the headlines on Monday, posting new all-time highs, but there were plenty of standout performances amongst the big miners.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Something went wrong. Please try again in a moment.
You're trying to view member-only content
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.