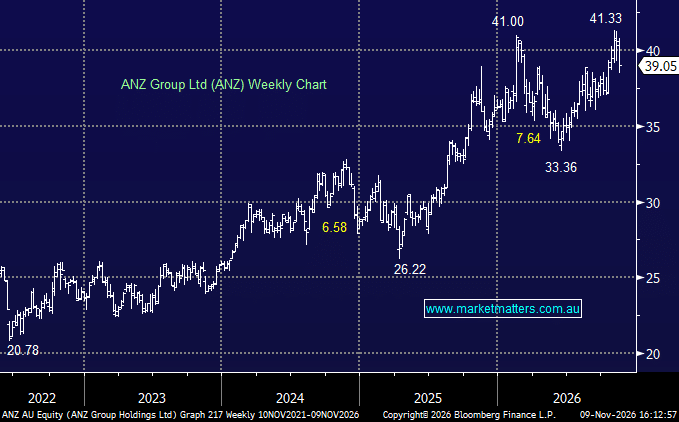
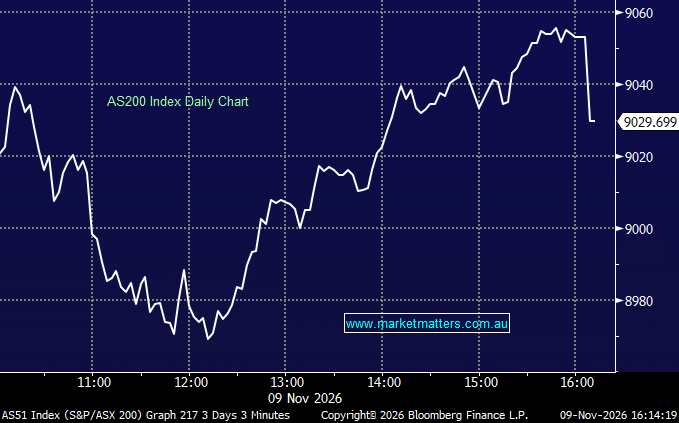
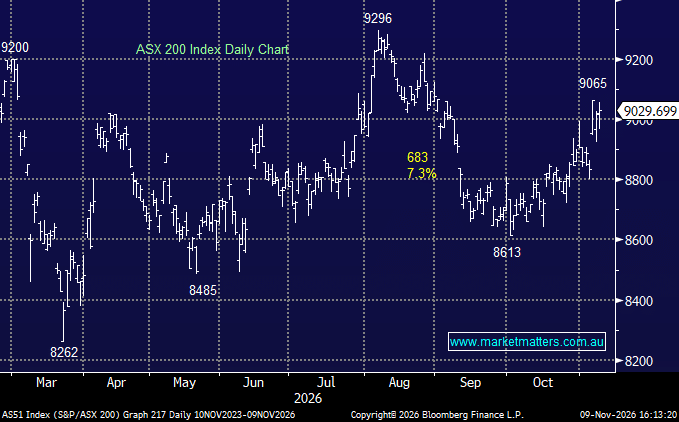
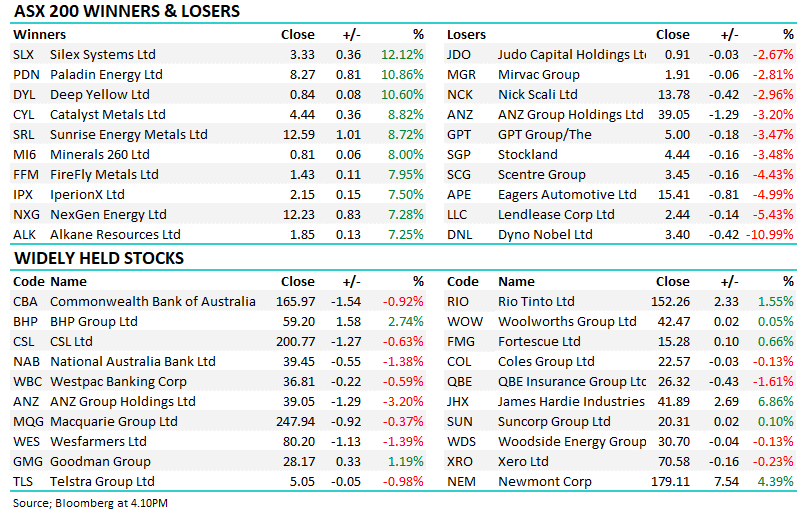
Australian shares managed a modest gain after a choppy session as a rebound in miners and technology helped offset pressure on banks and property stocks, with the market still navigating the fallout from last week’s sharp AI-led sell-off on Wall Street. ANZ was the major drag after a softer full-year result which triggered selling across the Big Four, while gold and copper strength supported a recovery across parts of the resources sector.
Aussie shares finished lower as Wall Street’s AI sell-off spilled into global markets, with miners and technology stocks bearing the brunt of fears around tighter data centre regulation and a potential slowdown in infrastructure spending.
A huge day for Aussie equities, with the ASX bouncing strongly following the US mid-term elections, a pullback in oil and lower bond yields. Technology led the charge, surging around 10%, while Materials ripped 7.5% higher - 8 of the 11 sectors finishing in the green. Energy and Financials were the notable laggards. Energy weakness was understandable as oil prices cooled, while NAB’s soft FY26 result was enough to put the kibosh on the banks, making the broader market move even more impressive.
Local shares moved lower through the day as US midterm results trickled in, with the Democrats taking control of the senate and triggering fears of tighter regulation across the AI and data centre industries, sending US futures lower and weighing on technology-linked miners.
The ASX ultimately finished Melbourne Cup Day higher, but it was was struggling into the RBA decision, trading down around ~40 points, before rallying after the Bank delivered the widely expected 25bp hike. The split 6-3 vote, together with a more balanced message from Governor
Aussie shares finished lower as the market braces for another RBA rate hike whilst also digesting Friday’s sharp US tech sell-off, with weakness in banks, miners and supermarkets dragging the bourse down. A solid result from Westpac sparked divergence across the banking sector, with the remainder of the Big Four closing lower, while small caps and technology stocks showed relative resilience.
It was shaping up to be a very strong finish to October for the ASX early today, with the index up almost 1% and briefly pushing back toward 9,000 for the first time since early September. Unfortunately, the strength didn’t last. The ASX steadily gave back most of its gains through the afternoon as weakness in global technology stocks, resources and selected growth names weighed, eventually closing ~80 points below the early session highs.
The ASX posted a solid session as select rate-sensitive sectors helped the market extend gains despite a hotter local CPI print yesterday, with banks and property shares leading after Wall Street rose on the Federal Reserve’s decision to hold rates overnight. Consumer stocks remained under pressure amid softening retail updates, while Materials came off the boil slightly, with lithium names particularly soft as Chinese spodumene prices fell.
The ASX gave back much of its early advance, with a ~90pt intraday reversal after hotter-than-expected inflation data lifted rate concerns. Miners and technology shares held up well as the market continued to respond positively to the Anthropic IPO filing yesterday, while Defensive sectors lost ground, reversing some of their recent outperformance
The ASX recovered from an early decline as Anthropic’s IPO filing revived global appetite for AI-related stocks just as stronger-than-expected Chinese economic data helped light a fuse under the Materials sector.
Aussie shares finished lower as Wall Street’s AI sell-off spilled into global markets, with miners and technology stocks bearing the brunt of fears around tighter data centre regulation and a potential slowdown in infrastructure spending.
A huge day for Aussie equities, with the ASX bouncing strongly following the US mid-term elections, a pullback in oil and lower bond yields. Technology led the charge, surging around 10%, while Materials ripped 7.5% higher - 8 of the 11 sectors finishing in the green. Energy and Financials were the notable laggards. Energy weakness was understandable as oil prices cooled, while NAB’s soft FY26 result was enough to put the kibosh on the banks, making the broader market move even more impressive.
Local shares moved lower through the day as US midterm results trickled in, with the Democrats taking control of the senate and triggering fears of tighter regulation across the AI and data centre industries, sending US futures lower and weighing on technology-linked miners.
The ASX ultimately finished Melbourne Cup Day higher, but it was was struggling into the RBA decision, trading down around ~40 points, before rallying after the Bank delivered the widely expected 25bp hike. The split 6-3 vote, together with a more balanced message from Governor
Aussie shares finished lower as the market braces for another RBA rate hike whilst also digesting Friday’s sharp US tech sell-off, with weakness in banks, miners and supermarkets dragging the bourse down. A solid result from Westpac sparked divergence across the banking sector, with the remainder of the Big Four closing lower, while small caps and technology stocks showed relative resilience.
It was shaping up to be a very strong finish to October for the ASX early today, with the index up almost 1% and briefly pushing back toward 9,000 for the first time since early September. Unfortunately, the strength didn’t last. The ASX steadily gave back most of its gains through the afternoon as weakness in global technology stocks, resources and selected growth names weighed, eventually closing ~80 points below the early session highs.
The ASX posted a solid session as select rate-sensitive sectors helped the market extend gains despite a hotter local CPI print yesterday, with banks and property shares leading after Wall Street rose on the Federal Reserve’s decision to hold rates overnight. Consumer stocks remained under pressure amid softening retail updates, while Materials came off the boil slightly, with lithium names particularly soft as Chinese spodumene prices fell.
The ASX gave back much of its early advance, with a ~90pt intraday reversal after hotter-than-expected inflation data lifted rate concerns. Miners and technology shares held up well as the market continued to respond positively to the Anthropic IPO filing yesterday, while Defensive sectors lost ground, reversing some of their recent outperformance
The ASX recovered from an early decline as Anthropic’s IPO filing revived global appetite for AI-related stocks just as stronger-than-expected Chinese economic data helped light a fuse under the Materials sector.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Something went wrong. Please try again in a moment.
You're trying to view member-only content
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.