When inflation rises it takes interest rates along for the ride which flows down to multiple contraction / a drop in valuations i.e. people are prepared to pay less for a company’s potential growth / yield because they can suddenly get an improving return on their risk free funds at the bank i.e. a major tailwind for stocks has become a headwind
The US literally pumped money / stimulus into their economy after the GFC but the amount pales into insignificance compared to their extreme efforts post-COVID, never in history has the global economy experienced such phenomenal economic stimulus effectively providing “free money” which has fuelled massive M&A and buyback activity in equities
MM believes that company buybacks are close to a point of inflection which should remove an enormous tailwind for stock indices i.e. one of the largest net buyers of stocks may retreat
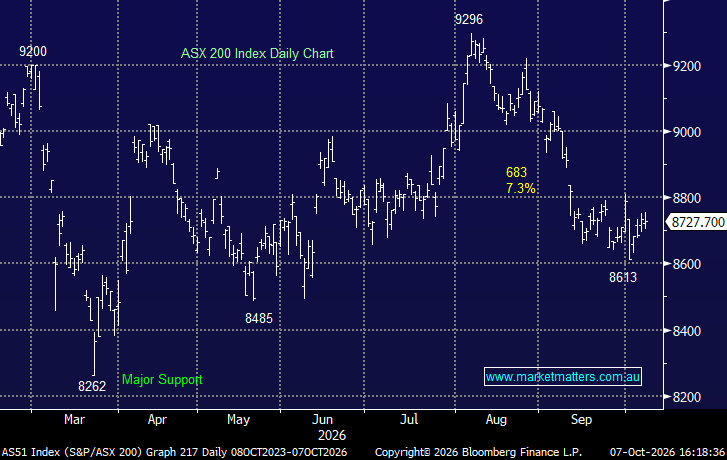
MM remains mildly bullish Australian equities looking for 4-6% further upside i.e. not a big call but we do anticipate reducing our risk if such a move unfolds
MM is looking for around 10% upside in copper in the coming months but we must remain mindful of how quickly some moves unfolded in 2020/21, in both directions!
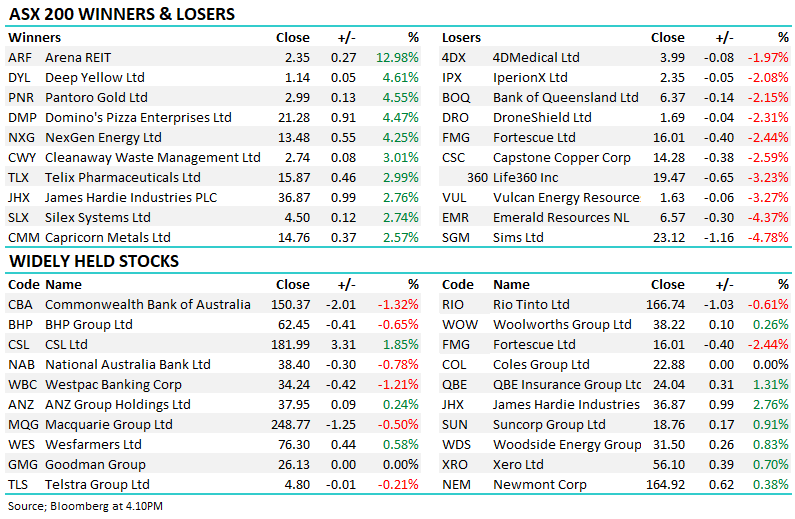
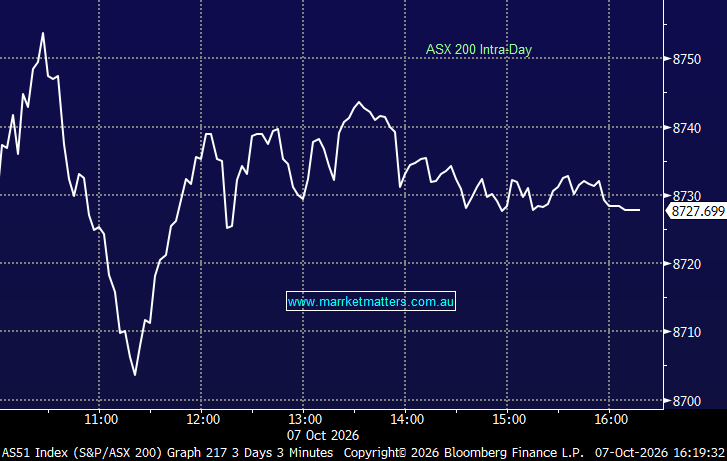
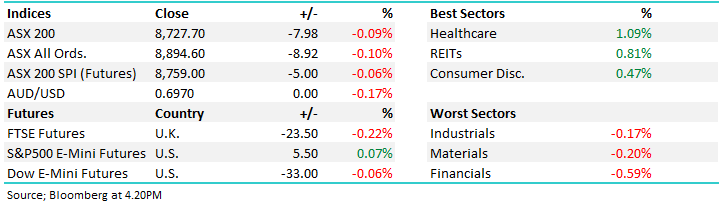
The ASX finished slightly lower today snapping a four-day winning streak as the market struggled to follow another record session on Wall Street. A majority six of 11 sectors finished higher, though the heavyweight sectors weighed on the bourse overall. Healthcare and Real Estate led the market, while Financials and Materials were the biggest drags.
The ASX advanced +0.6% on Tuesday on relatively broad based gains with over 60% of the main board closing higher. However, it was the rare combination of strength in both materials and financials that dragged the index higher, contributing ~86% of the days advance from a points perspective. What caught our eye was some buying coming back into some of the consumer facing stocks, ironically just as consumer confidence data plunged towards a 30-year low - there’s nothing quite like the combination of rising interest rates and cost-of-living pressures to squeeze everyday Australians, particularly when the holy grail of household wealth - property prices, are falling at the same time.
The ASX moved higher for a third straight session with some confidence returning to the market. The rally was driven by a very different mix of stocks to what we saw on Wall Street overnight, with Real Estate leading despite bond-yields remaining elevated, and Materials also looking strong. Technology was the only significant detractor, failing to mirror the move seen overnight in the US as the tech-focused Nasdaq surged to new all-time highs.
The financial press keeps telling us that stocks are expensive and a correction is inevitable, yet US markets remain within 1% of new all-time highs. The chart below tells an interesting story about the two factors pulling the S&P 500 in opposite directions through 2026. Blended forward EPS estimates have surged 35% since year-end, reflecting strong corporate earnings, particularly across AI-related companies, yet the index itself is up only +11.8%.
The ASX 200 finished a volatile week up +0.2%, almost as if Thursdays ~2% plunge to fresh four month lows didn’t exist. The weekly change masked significant volatility as investors digested the RBA’s fourth rate hike of 2026 alongside softer-than-expected inflation data. Technology was the standout sector, surging 7.3%, while the dominant theme remained interest rates, with the cash rate reaching a 15-year high of 4.6%, although softer CPI and Governor Bullock’s subsequent comments tempered expectations for further tightening.
The ASX bounced today following yesterday’s broad-based sell-off with the rebound driven by a recovery in Technology, while nine of the 11 sectors finished higher. The move leaves the index up +0.2% for the week after a volatile few sessions, with the market still looking for confirmation that the recent surge in bond yields and oil prices has potentially peaked.
The ASX 200 was walloped ~2% on the first day of October, registering its biggest daily fall in over six months on broad based selling which saw over 90% of the main board close lower. The selling was compounded by the index breaking to fresh 4-month lows, triggering momentum and trend following systems sell to more, erasing close to $60bn from the index in the process. We believe the aggressive nature of yesterday’s decline came down to three reasons.
Today's move was effectively the mirror image of yesterday with the ASX back to its lowest level since June. The market rallied almost 1% yesterday on softer CPI and hopes that the RBA may be close to the end of its tightening cycle, but bond yields reversed higher overnight and quickly put that trade under pressure.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.