Hi Peter,
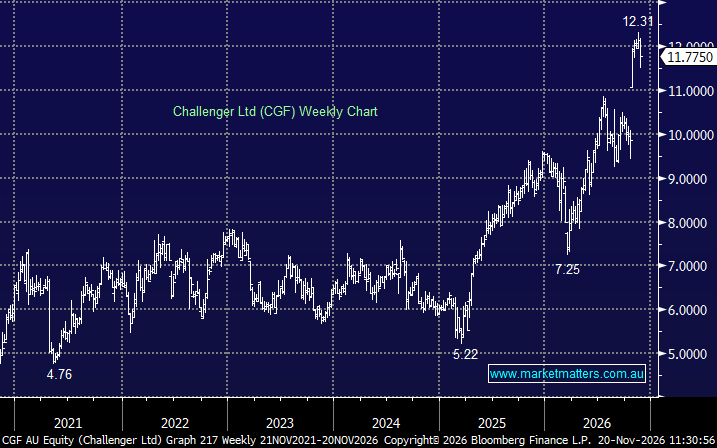
On Friday CGF was currently trading at $11.78, a ~3.5% discount to the rejected $12.20/sh bid, suggesting to us the markets expecting Tal Dai-Ichi to come back with a 3rd higher offer – remember it already owns 20.5% of CGF.
The boards rhetoric has become more constructive as the price has gone up, as it should:
- Rejection of the initial $11.80/sh offer (Oct 25): The board concluded the offer was “not at a level it could recommend to shareholders.” Despite rejecting it, the board agreed to engage with TAL DaI-Ichi to explore whether a proposal at an acceptable level could be reached.
- Rejection of the revised $12.20/sh offer (Nov 18): The board, after considering the terms with advice from financial and legal advisers, stated the revised offer “does not adequately represent fair value for shareholders in the context of a control transaction.”
CGF’s management has consistently avoided putting a public price on standalone fair value, instead pointing to strong capital, earnings growth, and ROE targets as justification for the board’s view that neither bid “adequately represents fair value in the context of a control transaction.”
- While we couldn’t buy CGF here from a risk/reward perspective we do believe TAL DaI-Ichi will come back a 3rd, and perhaps last time, in the $12.40-50 area.