Hi John,
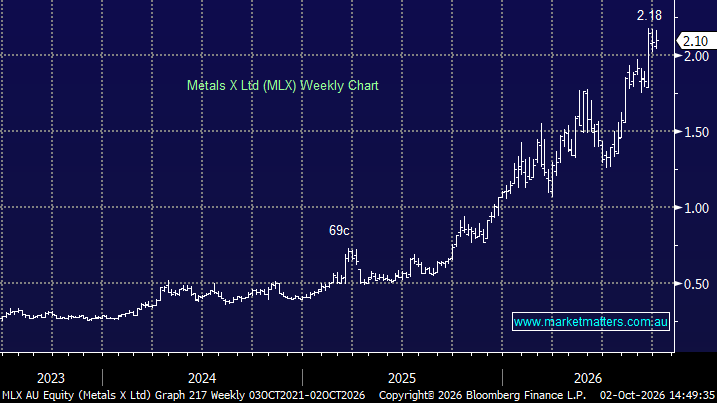
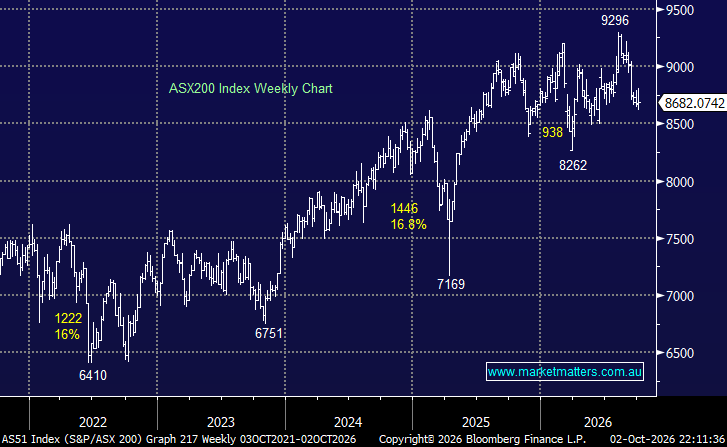
Metals X Ltd (ASX: MLX) – This $1.9bn primarily tin miner has more than doubled YTD, outperforming many of the better-known ASX mining names. The stocks strong performance in 2026 has been largely earnings-driven. While the ASX 200 Materials sector is up around 17% YTD, MLX has materially outperformed as consensus earnings expectations have been repeatedly revised higher, with the stock continuing to advance even as the broader resources sector softened over the past month.
- Forward EPS has risen from around $0.079 at the start of 2026 to ~$0.235 today, almost tripling, following four major upgrades.
Interestingly, MLX’s forward P/E has actually compressed from ~13.2x to ~8.3x, having fallen as low as 5.5x in July. The fundamental driver has been MLX’s 50% interest in Tasmania’s Renison Tin Operation, making the company primarily a play on the base metal tin. Hence, strong tin prices on higher production has improved earnings materially which has underpinned the stock price.
- Using the WisdomTree Tin ETF (TINM LN) as a liquid proxy for tin prices, the metal is up approximately +35% year-to-date.
The company’s increasingly strong balance sheet and capacity to fund growth or additional investments have provided further support. After such a strong run the risk/reward is naturally less compelling than it was earlier in the year, but at ~8x forward earnings the market is still not applying an aggressive multiple – we like MLX around $2.
Starpharma Holdings (ASX: SPL) – we were asked a question on SPL last month with the answer here. Its a huge ask for SPL to grow from $380mn to the $5.1bn market cap of Telix (TLX) despite more than doubling in the last year.
SPL and TLX are at very different stages of maturity. SPL is a pre-profitability platform company trading on a speculative valuation, while TLX is a scaled, profitable radiopharmaceutical commercial business now taking on significant leverage to vertically integrate its supply chain via the ITM deal.
- The odds are against SPL getting near to TLX as it burns cash but it is heading in the right direction.