Hi Charles,
We’ve never been called better than a sleeping pill before but we’ll take it! Thanks.
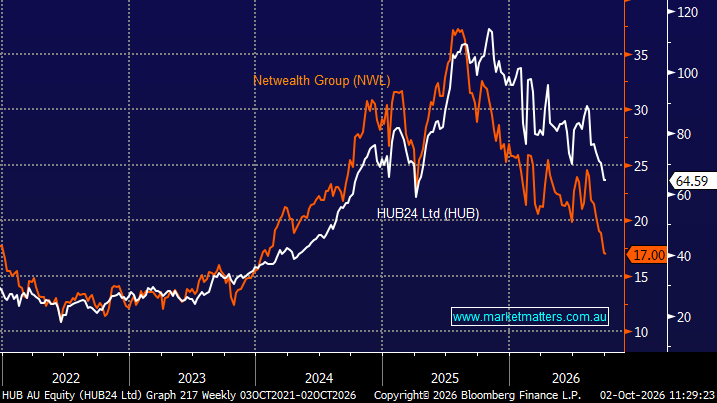
We do like HUB but not its share price of late with the stock suffering on three major fronts:
- Platform providers such as HUB, along with the broader software sector, have been under pressure from the “AI Disruption” Trade.
- Rising bond yields, especially at the long end, have weighed on high valuation growth stocks generally.
- FUA growth in the 2H26 slowed, and while there were clearly macro-economic and budgetary reasons for this (changing tax treatment), this is something we are watching closely.
In terms of buying HUB here, sub $65, the answer is yes, but weightings are important. We have a 4% target weight at inception, which is down 20%, hence is now nearer 3% prevailing weight. We think that is about right until we get the September quarter FUA numbers due on the 20th October. The market is concerned about slowing growth, which will either be confirmed or dispelled towards the end of this month. A more conservative path would be to wait until these numbers are released.
Regarding HUB v NWL, we still prefer HUB which we covered in detail in August, here, as it evolves further into a broader wealth-technology ecosystem, while Netwealth remains somewhat more platform-centric with a growing HNW/private-wealth offering – both are down ~34% YTD.