This brings us to Pinnacle Investment Management (PNI), which owns around 35% of Metrics. Metrics has been one of Pinnacle’s highest-profile affiliates, so the current situation is clearly a blemish, but the direct financial impact appears relatively manageable: Metrics represents around 13% of Pinnacle’s effective FUM and roughly 10% of recurring profits, meaning even a meaningful slowdown in Metrics flows should not derail the broader group.
The bigger issue is growth and reputation. Metrics is unlikely to be the significant contributor to new FUM that it has been in recent years, investor confidence has been dented, and redemptions could increase moving forward. Pinnacle’s decision to invest a further $100.5m in Metrics earlier this year also now looks very poorly timed, particularly given the subsequent issues and falls.
However, PNI is far bigger and more diversified than any single affiliate: Pacific Asset Management is now wholly owned, Life Cycle has become the group’s largest affiliate by FUM at more than $42bn, and international clients accounted for 33% of group FUM at June 2026. That diversification is central to Pinnacle’s model—individual affiliates can stumble, but the broader platform can continue to compound as successful managers grow and become increasingly important to group earnings.
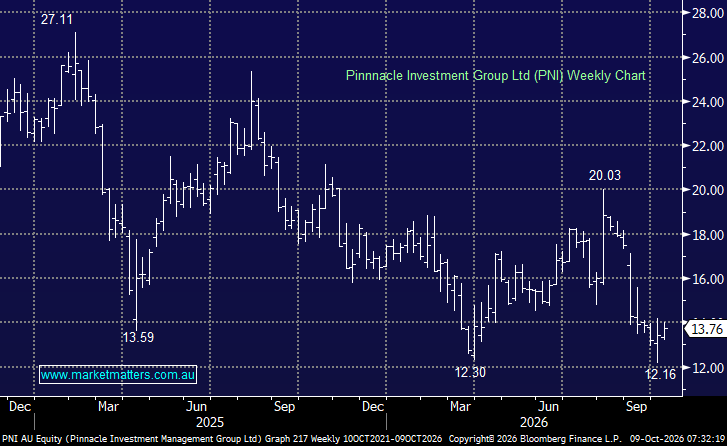
We discussed PNI in detail last month here, members should note that PNI is a platform rather than a bet on any individual fund manager, and its now trading ~40% below its long term valuation, i.e. there’s plenty of bad news already built into the share price. The market liked its FY26 result here, driving the stock initially up towards $20 – we thought it was a touch messy but the tape rarely lies, or in this case until Metrics came along.
For Pinnacle, we view Metrics as a setback rather than a thesis-breaker. The direct earnings exposure is manageable; the more significant concerns are the impact on Metrics’ reputation, future FUM growth and Pinnacle’s near-term growth trajectory. PNI has already fallen heavily, and at around 18x earnings it is cheap but given its sensitivity to markets, fund flows and investor sentiment it may remain so for a while. MM remains positive on PNI over the medium term, but we would accumulate gradually. Metrics is messy and private credit is going through a genuine test, but neither changes our broader view that Pinnacle remains a high-quality funds-management franchise with a diversified portfolio of affiliates and significant long-term growth potential.
- We like the risk/reward towards PNI below $14, initially targeting a retest of it August high around $20 – we own PNI in our Emerging Companies Portfolio.
MM is long and bullish towards PNI around $14
Add To Hit List