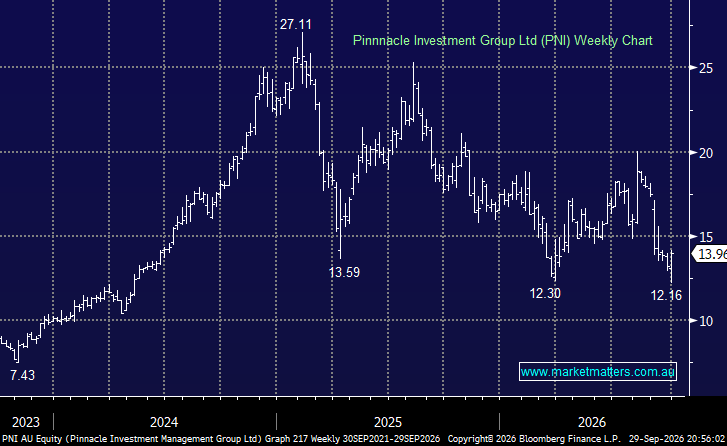
PNI was caught in the fallout from recent issues at Metrics, where the valuations of several funds were revised lower on Monday after a review of asset values and expected credit losses. The resulting NTA cuts were 2–12% across three listed Metrics vehicles, prompting a sharp sell-off in PNI, given their ~35% ownership of the credit manager, before a UBS upgrade sparked a strong bounce in the stock yesterday. With the revised valuations now clearer, the damage looks more contained than the initial market reaction suggested. The key question for us is whether a problem at one affiliate warrants a major reset to the value of the broader Pinnacle platform. At this stage, we don’t think it does.
NB Things got worse for metrics after the ASX closed yesterday: In a note to investors in its MCP Wholesale Investment Trust, which manages about $6 billion, Metrics said applications for redemptions of units would “not be accepted or processed”, i.e. investors cannot get their money out.
The important detail from the Metrics updates is that the NTA revisions, while meaningful, are well below the discounts at which the listed vehicles had already been trading:
- Metrics Real Estate Multi-Strategy Fund (ASX: MRE): NTA reduced from $2.53 to $2.22, a 12% haircut; trading at $1.68, a 25% discount to revised NTA.
- Metrics Mater Income Trust (ASX: MXT): NTA reduced from $2.00 to $1.96, a 2% haircut; trading at $1.62, an 18% discount to revised NTA.
- Metrics Income Opportunities Trust (ASX: MOT): NTA reduced from $2.15 to $1.93, a 10% haircut; trading at $1.755, a 9% discount to revised NTA.
NB Things got worse for metrics after the ASX closed yesterday: In a note to investors in its MCP Wholesale Investment Trust, which manages about $6 billion, Metrics said applications for redemptions of units would “not be accepted or processed”, i.e. investors cannot get their money out.
We still expect the suite of listed Metrics vehicles to see selling once they resume trading, but clearly the market had already applied severe discounting to NTA before the revaluations surfaced. The valuation review has identified pressure around fair values of equity positions and expected credit-loss provisions, and there is a risk of weaker flows into Metrics as investors reassess private credit. There is also the ongoing regulatory review of the sector. However, the key point for PNI is scale: PNI owns ~35% of Metrics, and the credit provider accounts for around 13% of effective FUM but only ~10% of recurring profits, meaning even a significant deterioration at the affiliate level does not fundamentally alter the economics of the broader group.
Pinnacle is a platform rather than a bet on any individual fund manager. Its model is to build and acquire stakes in specialist investment boutiques, then provide distribution and infrastructure that allows them to scale. Metrics is one of a much broader group of affiliates, including Hyperion, Plato, Solaris, Resolution, Antipodes, Firetrail and Coolabah.
The growth runway remains substantial. Aggregate affiliate FUM reached $229.4bn, with effective FUM of $102.4bn, and the platform has significant capacity to grow existing strategies. There are 35 strategies with meaningful performance-fee potential, with 18 currently at their high-water marks, representing 67% of relevant FUM. This is important because it means PNI doesn’t need Metrics to be firing on all cylinders to continue growing – the broader platform can keep compounding through new affiliates, existing strategies performing well and taking market share, and the expansion of international and retail distribution.
After the sharp sell-off, PNI was trading at around 14.5x forward earnings, versus a five-year average of roughly 24x. That is a meaningful de-rating for a business where the underlying earnings trajectory remains geared to FUM growth, investment performance and new affiliate development. The market is clearly assigning a higher risk premium to the business, and rightly so, but the question is whether it has gone too far.
The bigger risk from here is arguably not the immediate accounting impact from Metrics, but whether the episode causes a broader deterioration in flows or confidence across private credit and the Pinnacle platform. That’s what we’ll be watching. For now, the evidence points to a contained problem rather than a systemic one.
We hold PNI in the Emerging Companies Portfolio and are keeping our ear to the ground after this week’s announcement, though we remain comfortable owning the stock. The Metrics issue is a legitimate negative, but the NTA adjustments have been smaller than the discounts already applied to the listed vehicles. PNI is one of our higher-beta holdings, and that is part of the reason we own it. In the current environment, we’d rather maintain exposure to businesses capable of strong earnings compounding than retreat from them after a sharp de-rating.
MM remains long and bullish PNI
Add To Hit List