WBT is a $860mn semiconductor technology company developing ReRAM (resistive random-access memory), a next-generation non-volatile memory technology designed to retain data without power while offering advantages in speed, power consumption and scalability. Rather than manufacturing chips itself, WBT licenses its intellectual property to semiconductor manufacturers and foundries, with the investment case centred on converting its technology into widespread commercial adoption and recurring royalty revenues.
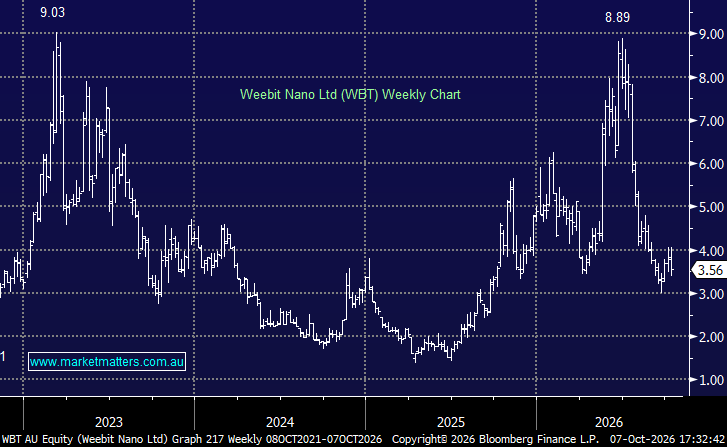
WBT earned promotion to the ASX 200 in September following an amazing run, with the stock surging ~600% in just over 12-months, lifting its market capitalisation from around $290m to more than $2bn. The rally reflected enthusiasm for WBT’s ReRAM semiconductor memory technology amid the global AI boom, reinforced by milestones including its selection for a Korean government-backed program developing ultra-low-power compute-in-memory technology for AI applications. Ultimately, the surge in its market cap pushed WBT sufficiently far up the rankings to qualify for the index.
However, the same momentum that propelled WBT into the ASX 200 has subsequently gone sharply into reverse. The shares have fallen ~60% from their June peak, reducing the company’s market value to less than $900mn. The correction coincided with a broader unwind in high-beta AI and semiconductor stocks, but WBT’s pre-revenue status has magnified the decline. Without meaningful earnings to anchor its valuation, the stock remains highly sensitive to changes in sentiment and expectations around the commercialisation of its technology.
WBT demonstrates the risks surrounding momentum-driven index inclusion. The AI and semiconductor narrative drove a spectacular re-rating that ultimately secured its place in the ASX 200, but much of that move has already unwound. As we discussed earlier, index inclusion reflects where a company has been in the market-cap rankings, it provides no guarantee it will remain there, particularly for pre-revenue businesses where valuations can move dramatically ahead of fundamentals.
- At this stage of its evolution we feel WBT is more of trading, as opposed to investing stock
MM is neutral towards WBT
Add To Hit List