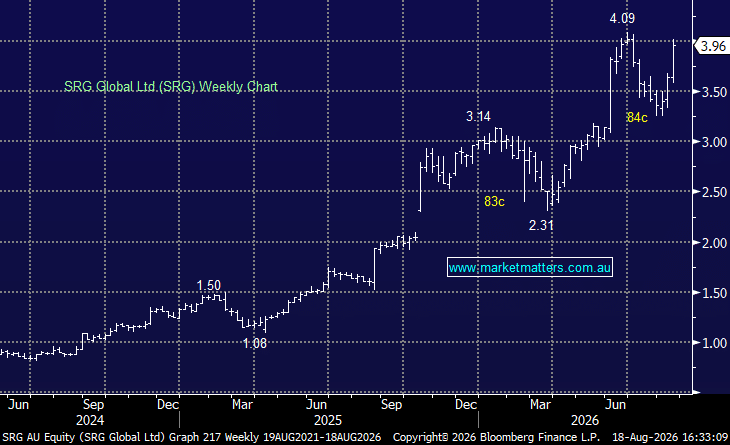
SRG +9.39%: Posted a strong FY26 result, with earnings and revenue ahead of expectations and management upgrading FY27 EBITDA guidance. The combination of double-digit earnings growth, a large work-in-hand position and an increasingly recurring earnings base continues to improve the quality and visibility of SRG’s growth profile.
Key results:
- Revenue of A$1.68bn, up 27% and ~2% ahead of A$1.65bn expected.
- Earnings (EBITDA) of A$170.1m, up 34% and ~2% ahead of A$167.4m expected.
- Net profit (NPAT) of A$71.9m, up 51% and broadly in line with A$71.6m expected.
- Final dividend of 4cps.
SRG upgraded FY27 earnings (EBITDA) guidance to A$195–205m, from A$190–200m previously, implying another 15–21% growth on FY26. Visibility remains a key strength, with A$5.1bn of work in hand and an A$11.5bn opportunity pipeline. The shift toward recurring maintenance and asset-services contracts rather than one-off construction projects continues, with around 80% of earnings now annuity or recurring in nature.
MM’s view: Another strong result from SRG, with the FY27 upgrade reinforcing the momentum in the business. We particularly like the evolution away from being viewed simply as a project-based contractor toward a business with a high proportion of recurring earnings and strong forward visibility. With EBITDA already up 34% in FY26 and management guiding to another double-digit increase in FY27, SRG continues to execute well.
MM remains bullish toward SRG
Add To Hit List