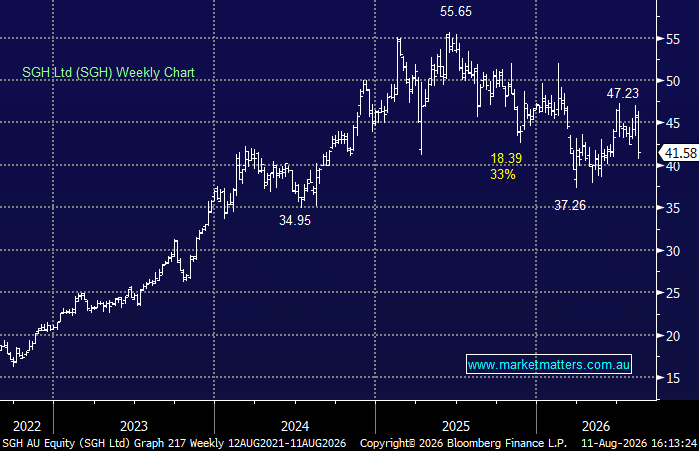
SGH –10.27%: Delivered a softer-than-expected FY26 result, though the bigger disappointment was a conservative FY27 outlook for flat to low-single-digit earnings (EBIT) growth.
Key FY26 results:
- Revenue of A$10.59bn, down 1.4%.
- Underlying EBIT of A$1.55bn, up just 1.1%, versus consensus expectations for ~2% growth.
- Underlying NPAT of A$920.1m, down 0.4%.
- Final dividend of 32c per share.
- SGH reiterated its previously announced A$500m on-market buyback, which will commence following the result.
Management expects flat to low-single-digit EBIT growth in FY27, with the focus shifting toward operational efficiencies, sales execution and extracting greater operating leverage across the portfolio through the “SGH Way”. The $500m buyback should provide some support, while SGH retains significant balance sheet flexibility for acquisitions.
One area we continue to find interesting is SGH’s exposure to Australia’s rapidly expanding data-centre buildout. Management estimates the opportunity at around $100bn, and SGH can participate across several parts of the construction chain: WesTrac provides standby and prime-power generation, Boral supplies concrete, Coates provides equipment, while its energy interests provide exposure to the gas required to support increasingly power-hungry infrastructure.
MM’s view: This wasn’t a bad result, but SGH has set a high bar through consistent execution, making a modest miss and subdued FY27 outlook enough to trigger some profit-taking. We continue to regard SGH as one of the ASX’s better industrial operators, with quality businesses, disciplined capital allocation and growing exposure to infrastructure and data centres. However, after a strong run, expectations were elevated. A near-10% pullback makes the risk/reward more interesting; the company remains on our Hitlist.
MM remains cautiously bullish toward SGH
Add To Hit List