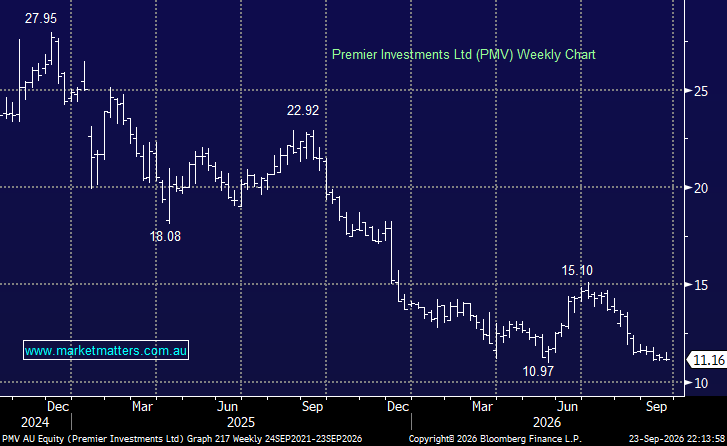
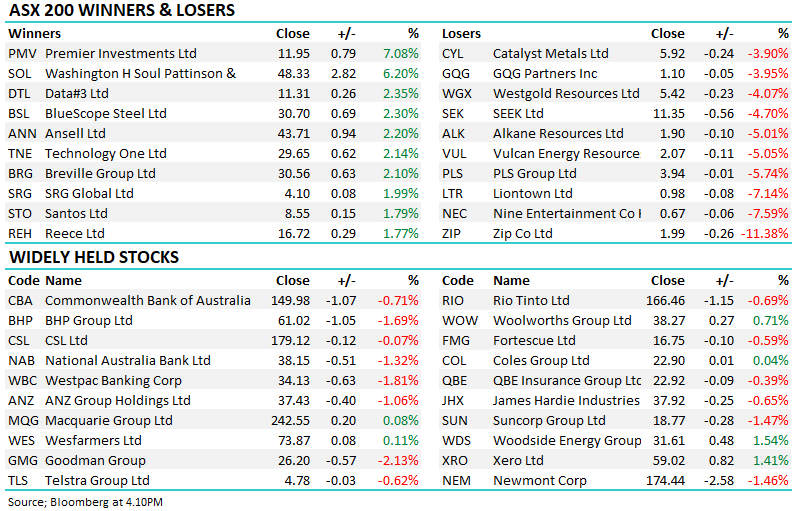
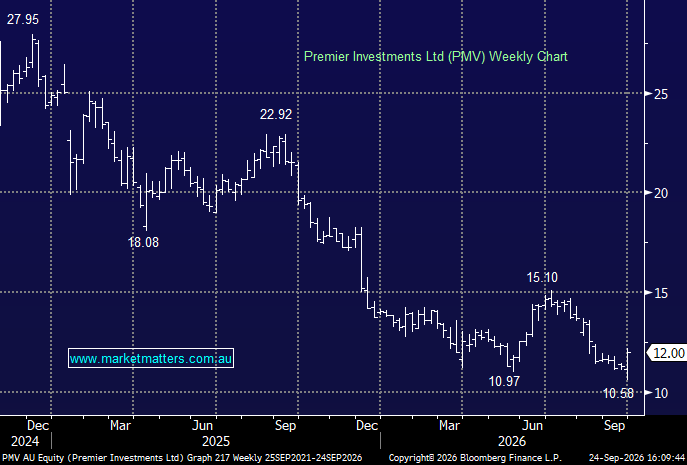
Unlike other stocks looked at today, PMV delivered a disappointing trading update in August, covered here, with discretionary spending weighing on sales – a common thematic. PMV has fallen around 40% over the past year, materially underperforming both the ASX 200 and Consumer Discretionary sector. Again, the decline has been driven overwhelmingly by multiple compression rather than collapsing earnings, with the forward P/E falling around 40% from 19x to 11.4x, while forward EPS declined just 9%. Investor confidence has been hit by repeated earnings disappointments, particularly weakness at Smiggle, with Premier Retail EBIT already falling 18% in FY25 before FY26 brought further downgrades.
As touched on, the latest setback came in August, when FY26 Premier Retail sales fell 2% to $795.5m and underlying EBIT guidance was cut again to around $176m, while Premier also decided to close Peter Alexander’s three UK stores. With the shares now trading near their 52-week low and on just 11.4x forward earnings, a substantial amount of disappointment has been priced in; however, a sustained recovery will likely require evidence that Smiggle has stabilised, Peter Alexander can maintain its domestic momentum, and earnings downgrades have finally run their course.
- We can see PMV trading between $10 and $15 moving forward; hence, the risk/reward is improving fast, helped by a forecast of more than 8% fully franked yield.
MM is bullish towards PMV in the $10-10.50 area
Add To Hit List