We have had NVIDIA (NVDA) on our International Equities Hitlist for some time, and today we pose the question: should we bite the bullet and pay up?
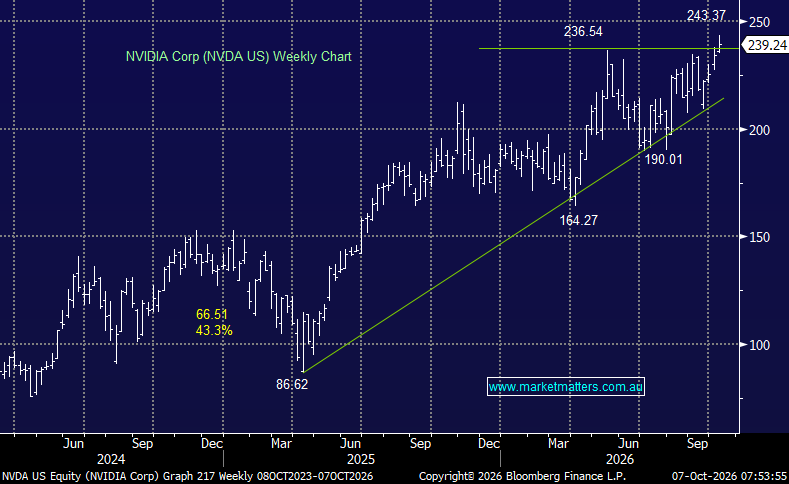
NVDA has spent around five months consolidating while earnings have continued to grow strongly. The share price has effectively gone sideways while the denominator in the P/E equation has risen, making valuation more attractive despite the stock now trading at record levels.
The technical picture has also strengthened. NVDA has broken above its prior high around US$236.50 and out of its multi-month consolidation, while the rising trend from the April low remains intact. We have no issue buying strong companies when price action confirms the fundamentals rather than trying to pick the low.
The earnings story remains exceptionally strong. On consensus numbers, EPS grows to US$9.37 in FY27, US$15.85 in FY28 and US$21.44 in FY29, versus US$4.77 in FY26. At current prices, this equates to an earnings multiple of around 25x FY27 and 15x FY28, with earnings growth averaging ~65% p.a. over that timeframe. So, even though NVIDIA’s share price is higher, its valuation has become more reasonable because earnings have grown even faster.
The balance sheet is also becoming formidable. On UBS forecasts, net cash will rise to around US$283bn by FY28, while NVIDIA has increased its buyback authorisation to US$235bn through FY28. UBS retains a Buy rating and US$300 price target.
So, why consider buying now? Earlier this year, our concern was not NVIDIA’s quality, but the combination of a huge share-price move, lofty expectations and uncertainty around the durability of AI spending. Since then, the stock has consolidated, earnings expectations have kept rising, valuation has compressed and the technical picture has improved.
We have clearly missed the recent pullback, but that does not mean we are too late. Our process is not about buying at the cheapest possible price; it is about buying when earnings momentum, valuation and price action align.
There are still risks around hyperscaler spending, competition and margins, but these are well understood and, in our view, increasingly reflected in the price.
The bottom line is that NVIDIA is one of those rare companies where earnings growth has been so strong that a rising share price has not necessarily meant a rising valuation. After several months of consolidation, the stock has now broken to fresh highs while earnings continue to support further strength.
There is also an element of chasing performance in this call. The International Equities Strategy has underwhelmed over the past 6-12 months, with below-benchmark exposure to the AI boom. We believe the runway for AI and associated companies remains a long one, and our allocation to this area has been too modest.
We recently added Applied Materials (AMAT US) to the portfolio, hold Microsoft (MSFT US) and Alibaba (BABA US), have exposure to data centres through IREN (IREN US), and more indirect exposure to the theme through Pershing Square (PSHZF US), Blackstone (BX US) and Cameco (CCJ US) on the energy side. However, we remain underweight direct semiconductor exposure.
- We are becoming more comfortable paying up for NVDA around current levels, with a preference to start with a smaller position rather than wait indefinitely for a pullback that may not come.
MM remains bullish NVDA US ~$US240
Add To Hit List