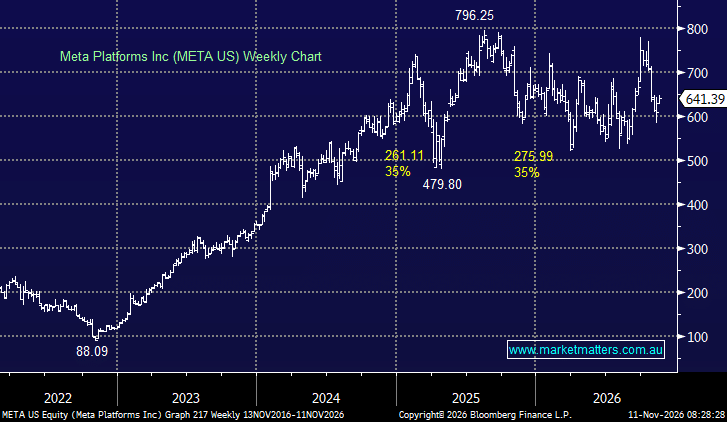
As followers of the International Equities Portfolio would appreciate, we have been underweight technology over the past 12 months, which hurt relative performance for much of the year, although that positioning has helped more recently as the AI trade corrected. We are now looking to selectively increase technology exposure into weakness, and Meta Platforms (META) is one of the names we like.
The key attraction is that Meta, unlike many others, is demonstrating how its enormous AI investment can be monetised. The first benefit is already visible in the core advertising business. AI is improving ad targeting, generating better creative content and lifting engagement through more effective content recommendations. Revenue growth has accelerated from around 22% in 2025 to an estimated 27% in 2026, demonstrating that the technology is already contributing to the existing earnings engine.
The second opportunity is more exciting: new consumer and business AI agents. Meta has recently launched its Muse family of models, the Muse personal agent and the Meta Enterprise Platform (not available in Australia yet). Muse appears to have gained traction very quickly, surpassing 10 million downloads within weeks, with early use cases ranging from travel bookings and appointment management to customer service and negotiating household bills.
The competitive advantage is their distribution scale. Meta already has access to nearly four billion users across its apps, deep knowledge of user interests and social connections, and integrations with major platforms such as Shopify, Walmart and Gmail. Few companies can launch an AI agent at that sort of scale.
Importantly, Meta can afford to offer Muse free to most users initially, build adoption aggressively, and monetise later through areas such as transaction fees and commerce. The Enterprise Platform applies the same logic to the hundreds of millions of businesses already using Meta to reach customers.
The AI debate around Meta is changing. Earlier in the year, we could see the enormous compute spend but had limited visibility on what would justify it. Today, Meta is demonstrating multiple monetisation pathways — stronger economics from the existing advertising business, plus entirely new consumer and enterprise products.
- With the stock having pulled back from recent highs, we think the risk/reward has improved. As we selectively increase technology exposure into weakness, META stands out as a solid way to gain AI exposure with a highly profitable core business already funding the investment.
MM is bullish on META US ~US$640
Add To Hit List