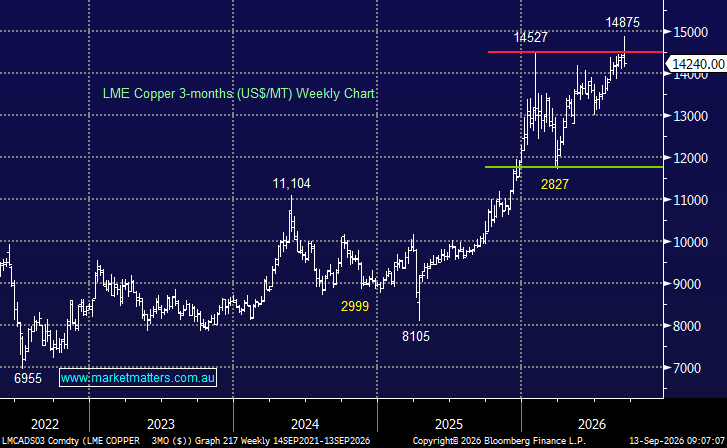
Copper just posted its 11th weekly gain from the last 12, as renewed Chinese buying helped the metal rebound from the sharp correction that followed its record high. Copper still feels vulnerable to news around US tariffs with the market long and watching President Trumps meeting with Chinese President Xi this week very closely.
Thursday’s Trump-Xi summit at the White House, could be a pivotal event for the ASX miners with tariffs, AI and rare earths expected to dominate discussions following preparatory talks between US Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng over the weekend. Markets will be watching for signs of a tariff truce or delay to the next tranche of Section 301 duties, either of which could provide some welcome relief from US-China trade tensions.
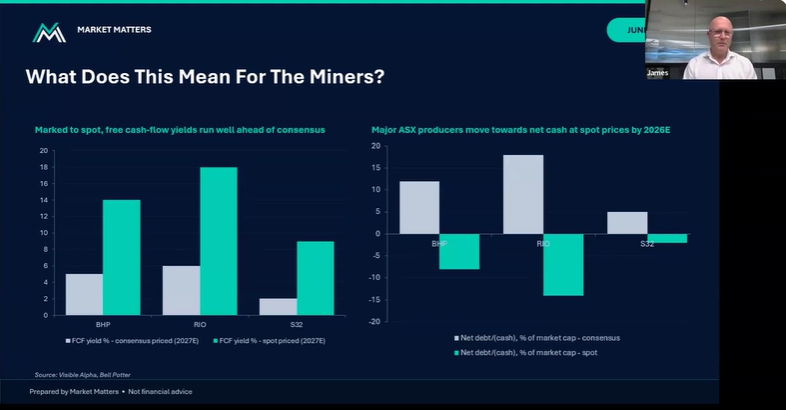
- Supply and demand continues to support copper but related miners feel nervous having underperformed the industrial metal in recent weeks.
Encouragingly, copper rallied last week despite the Fed raising rates for the first time since 2023, with stronger Chinese demand ultimately proving the more powerful influence. The Yangshan import premium increased and Shanghai spot premiums reached their highest level of 2026, while reports that Washington could delay further China tariffs also helped sentiment. The US dollar strengthened modestly following the Fed decision, limiting some of the upside, but the underlying demand signal from China was bullish.
The broader bull case remains intact supported by constrained mine supply, particularly in Chile, the world’s largest copper producer, where output has reportedly fallen around 7%. After such a powerful run, volatility should be expected, but copper’s ability to quickly rebound from the previous week’s correction reinforces the tailwind from rising demand and constrained global supply.
- We remain bullish towards copper, longer term but another correction cannot be ruled out – we’ve already had two in the last 3 years despite Cu’s strong bullish advance.