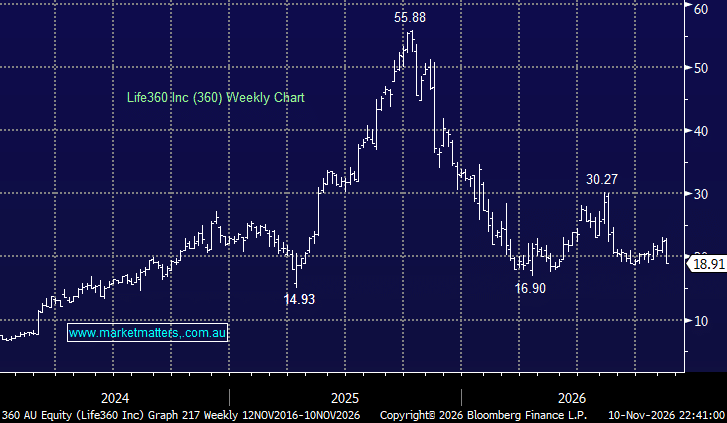
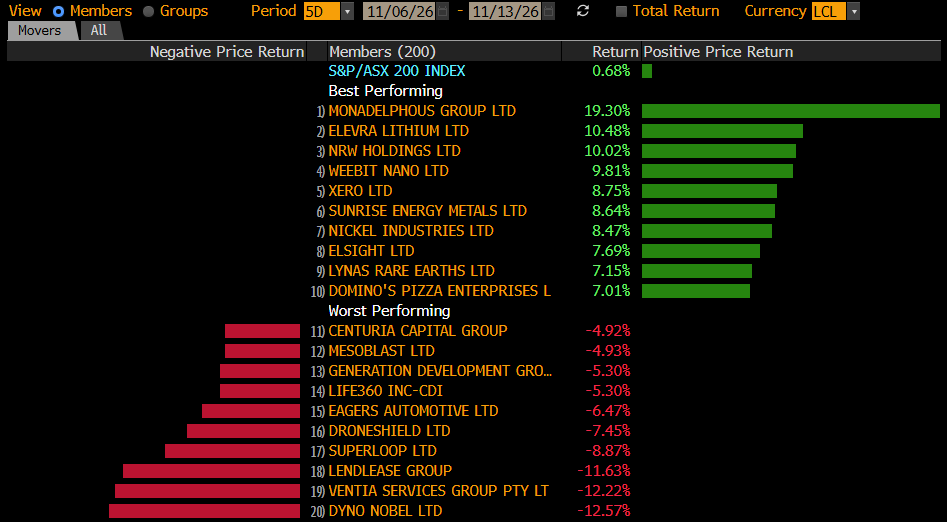
Life360 (360) fell more ~15% yesterday following its 3Q27 result, despite delivering strong headline growth. Revenue rose 40% YoY to US$174.1m, adjusted EBITDA increased 41% to US$34.6m, and EPS of US$0.26 – all comfortably ahead of consensus.
However, the issue was parts of their outlook:
- FY26 revenue guidance was narrowed to US$665–681m from US$650–685m – the market was at ~US$674m, so top line was not the issue.
- Adjusted EBITDA guidance tightened to US$132–138m, leaving the midpoint broadly unchanged v consensus (US$135m) – again, no issues there.
- However, Management said monthly active user growth is tracking toward the lower end of the 17–20% growth range – which explains some of the weakness.
- Advertising revenue guidance was also narrowed, which disappointed given this is an important higher-margin growth opportunity.
- And higher costs were also an issue, coming in at $US126m for the quarter, about US$4m more than hoped.
There were still plenty of positives – paying circles grew strongly, US pricing changes are showing encouraging early results, and advertising revenue continues to scale quickly. However, operating expenses are also rising quickly, while cash flow growth has not kept pace with the headline revenue growth.
The share price has been in the drain for a while, but even after the sell-off, consensus forecasts imply a sharp earnings ramp from here, with adjusted EPS expected to rise materially through FY27 and FY28 (~20% pa). The reaction looks harsh on the headline numbers, but the softer MAU trajectory and reduced advertising expectations explain it.
- We continue to hold Life360 in the Emerging Companies Portfolio, acutely aware that we’ve held on too long – yesterday’s update needed to be better.
MM remains patiently long 360 (for now)
Add To Hit List