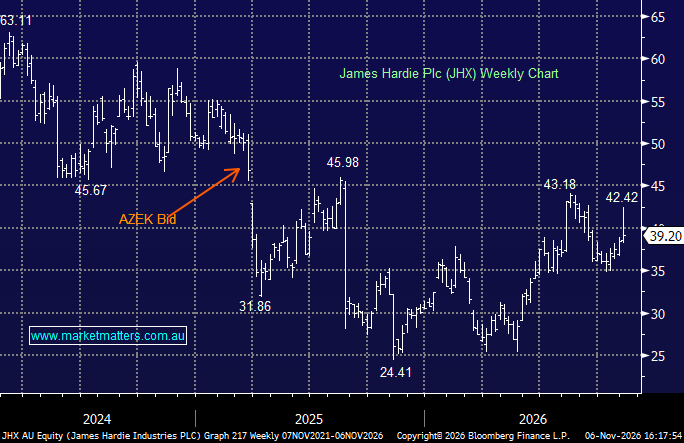
JHX -6.22%: Reported a softer-than-expected 2Q27 result, with net sales missing consensus and its 3Q27 forecast coming in below market expectations. Despite continued growth in North America and Australia & New Zealand, the near-term outlook remains challenging.
Key details:
- 2Q net sales of US$1.43bn, below the US$1.45bn consensus.
- Adjusted earnings (EBITDA) of US$454.7m and adjusted net income of US$248.5m.
- 3Q sales guidance of US$1.06–1.14bn, below the US$1.2bn consensus.
- North American fiber cement and Deck, Rail & Accessories delivered double-digit growth.
- Australia & New Zealand continued to benefit from market share gains.
- FY27 sales and EBITDA outlook reaffirmed, with free cash flow target increased.
MM’s view: The weaker third-quarter outlook is disappointing and points to near-term softness, despite positive underlying performance in North America and Australia & New Zealand. Management reaffirmed FY27 guidance and increased the free cash flow target which provide some reassurance, though the focus is now on whether the company can improve the second-half picture and beat rather than just meet the full-year earnings forecasts.
MM is neutral towards JHX
Add To Hit List