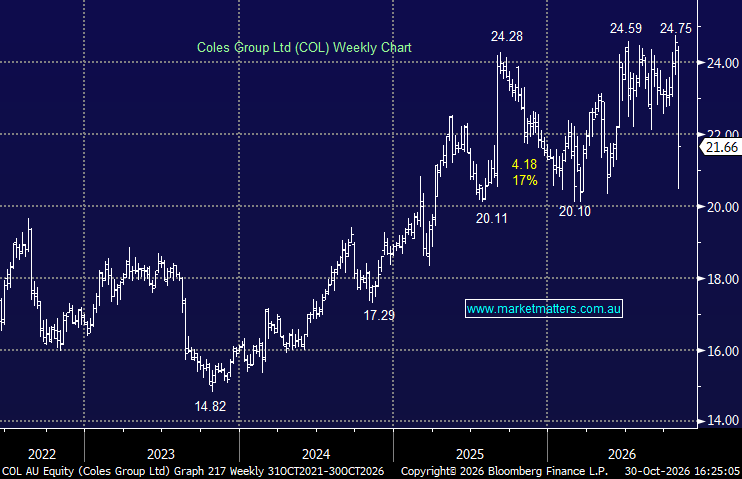
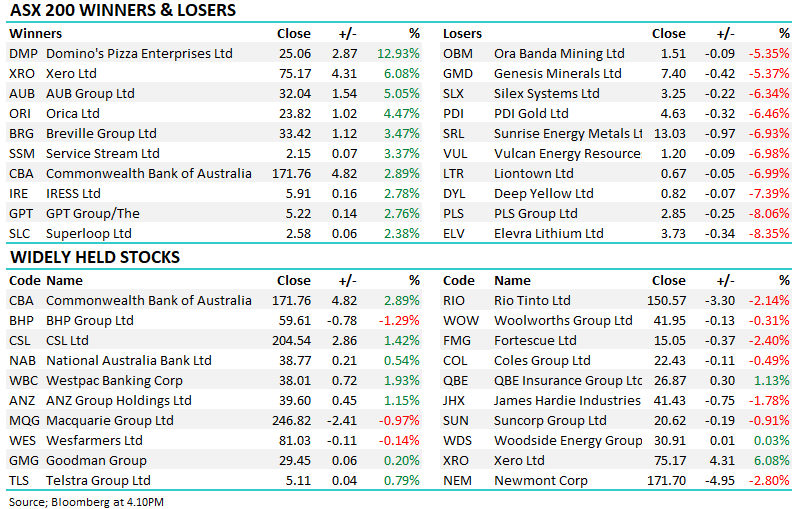
COL -7.67%: was hit hard today, falling around 7% after being down as much as 12%, after a disappointing Q1 update showed supermarket sales growth lagging Woolworths by a much wider margin than expected. The bigger concern is that management is now sacrificing near-term earnings growth to invest in lower prices and rebuild sales momentum.
Key Q1 highlights:
- Group sales: A$11.21bn, up 2.2% YoY.
- Supermarket sales: A$10.32bn, up 3.6% YoY.
- Supermarket comparable sales: up 2.7%, versus 4.6% a year ago.
- Supermarket price inflation: 1.1%.
- Liquor sales: A$831m, down 1.3% YoY.
- 1H Supermarkets EBIT is now expected to be broadly flat YoY.
The issue is the relative performance. Woolworths reported comparable Australian Food sales growth of 6.1%, versus just 2.7% for Coles, suggesting meaningful market-share pressure. While Woolworths benefited from Ooshies early in the quarter, its momentum appears to have held up reasonably well after the promotion ended.
Coles is responding by investing harder in price and promotions heading into Christmas. That makes strategic sense given consumers are increasingly focused on value, but it comes at a cost. Higher fuel expenses are already squeezing margins, while deeper price investment introduces the risk of a broader supermarket price war just as cost pressures are rising. Good for consumers, not so much for the sellers. If Woolworths responds aggressively, sector profitability could come under pressure.
We think today’s selloff reflects a genuine deterioration in the near-term earnings outlook rather than an overreaction to one soft quarter. Coles remains a high-quality business, but Woolworths has regained momentum at an awkward time, while the consumer is becoming increasingly price sensitive. The stock is clearly more interesting after today’s fall, but we would want to see evidence that the pricing response is improving volumes without causing a sustained margin reset before becoming more constructive.
MM remains neutral COL ~$21.60
Add To Hit List