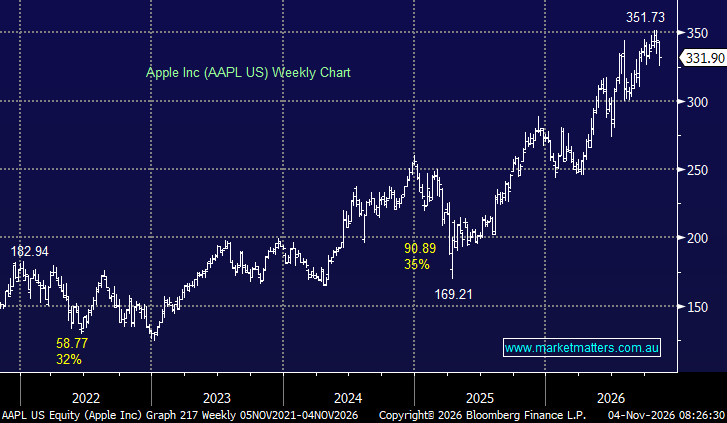
Apple (AAPL) reported after the close on Monday and delivered a mixed fourth-quarter result, with revenue and EPS ahead of expectations, but weaker Services growth, softer China revenue and a lower-than-expected margin outlook overshadowing the beat. The stock fell ~2% overnight, which is understandable given Apple had enjoyed a strong run into the result.
Key Q4 highlights:
- Revenue: US$114.5bn, up 12% YoY, ahead of US$113.5bn expected.
- EPS: US$2.10 vs US$2.00 expected.
- iPhone revenue: US$57.6bn, up 17%, ahead of expectations.
- Mac revenue: US$10.8bn, up 24%, also comfortably ahead.
- Services revenue: US$31.6bn, up 9.8%, broadly in line but slowing to single-digit growth.
- Greater China revenue: US$17.5bn, up 21% but well below the US$18.8bn expected.
- iPad revenue: US$6.2bn, down 10% and below expectations.
- Wearables, Home & Accessories: US$8.3bn, down 7.9%.
The hardware side of the business was actually quite strong, particularly iPhone and Mac. The bigger issue was the outlook. Apple guided to 7–10% revenue growth for the December quarter, ahead of consensus, but expects gross margins of only 45–46% versus around 47% expected, with higher memory costs and spending on its new Siri AI platform weighing on profitability.
Services is another area that mildly came off the boil. Growth of 9.8% remains healthy, but it has slowed materially from prior periods, important because Services carries significantly higher margins and has been a major driver of Apple’s earnings quality and valuation premium. China was also softer than hoped, despite still growing strongly year-on-year.
The AI story remains a little unusual compared with the other mega-cap technology companies. Apple has largely avoided the enormous infrastructure spending undertaken by Microsoft, Alphabet and Meta, which helped the stock outperform during the recent AI sell-off. However, R&D spending still rose 32% YoY to US$11.7bn, and the market will increasingly want to see evidence that Apple Intelligence and the new Siri can translate into stronger device demand or Services revenue.
MM’s view: Not a bad result, but expectations had become high. iPhone and Mac were strong and the holiday-quarter revenue outlook was encouraging, but weaker Services momentum, the China miss and margin pressure make it harder to justify Apple’s elevated valuation, now trading on 35x relative to the S&P 500 on 23x.
We still think Apple is an exceptional business, but the next leg higher probably requires evidence that AI can drive either a stronger upgrade cycle, faster Services growth or both. MM does not own Apple.
MM is neutral AAPL ~US$330
Add To Hit List