Hi Phil,
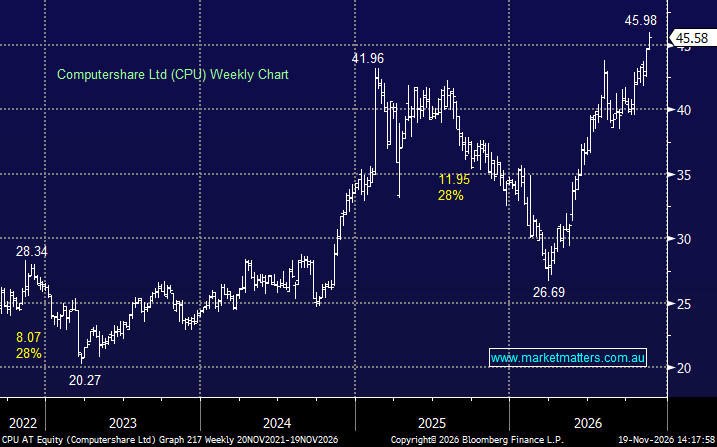
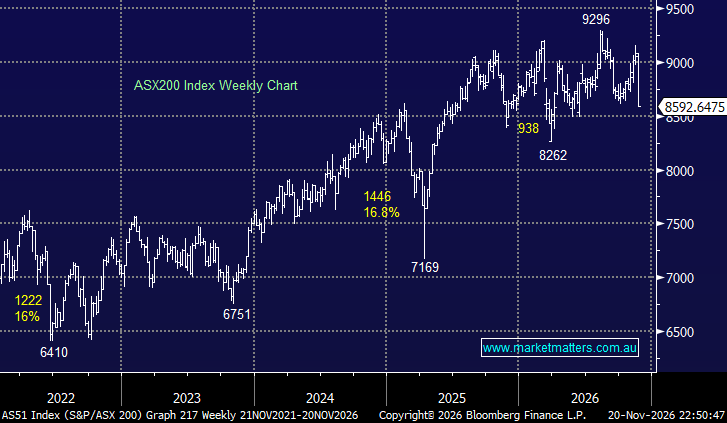
Computershare (CPU) is an excellent example of the strong getting stronger in 2026 – we’re sure you’re enjoying the ride! So far this year, CPU is up around 33%, while the ASX 200 is effectively unchanged.
We do cover CPU, although our last detailed discussion was just under a year ago here, when we adopted a bullish stance around $34. In hindsight, we should clearly have followed our own conviction, bought the stock and covered it more closely!
The past 12 months have been stellar for CPU, with its recovery driven by improving earnings expectations and greater confidence in the balance sheet. However, the stock really found another gear following its FY26 result, when management guided to ~6% growth in FY27 EPS, reinforcing confidence in the earnings trajectory.
- The latest catalyst came this month, with Computershare upgrading FY27 margin income guidance from ~US$770m to US$805m, comfortably ahead of the US$789m expected by analysts.
Importantly, the rally has been supported by genuine earnings upgrades rather than simply multiple expansion. For MM, CPU’s strength reflects a combination of earnings resilience and improving margin income, although after such a strong recovery, further upside will increasingly need to come from earnings growth rather than a higher valuation.
The stock is now trading on 19.2x earnings, having traded as low as 13x in March.
We like almost everything about Computershare, except its share price! Above $45, it looks fully valued to us, leaving us neutral at current levels. That said, there’s no obvious reason to fight the tape while the earnings momentum remains positive.