Hi Richard,
We covered the NHC hybrid on Wednesday here, we liked it and weren’t surprised demand was so strong.
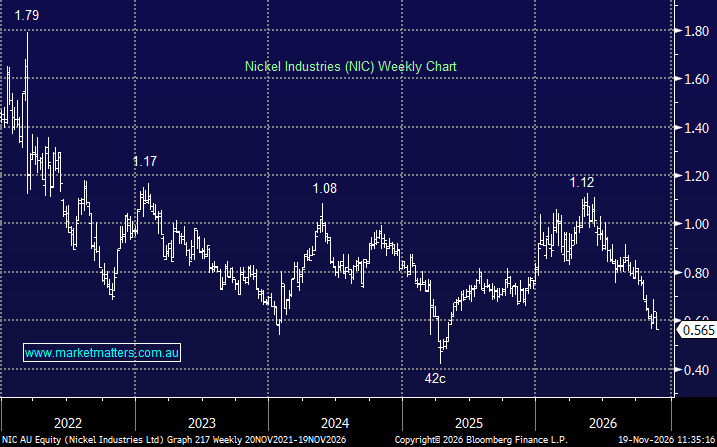
Our first thought looking at NIC trading at 56.5c on Thursday was “don’t fight the tape” with the stock trading down 50% below its May high, driven by a combination of weak nickel prices and operational setbacks in Indonesia, but at some stage value comes back into such cyclical miners.
Weak second-quarter adjusted earnings (Ebitda) hasn’t helped; it came in at $120m falling well short of the $135.6m achieved in the March quarter. Sentiment deteriorated further in September when dry conditions restricted water supply at its 46%-owned Excelsior Nickel Cobalt (ENC) project in Indonesia, limiting production to around 30% of capacity after initially reaching 50% shortly after commissioning.
However, the combination of weak nickel prices, a disappointing HPAL ramp-up in Indonesia, regulatory/geopolitical overhang, and a ~42% cut to forward EPS estimates is making NIC start to look interesting.
The company is profitable and forecast to grow earnings significantly through FY2028, but elevated leverage (~3.9x debt/EBITDA) and Indonesia execution risk remain the key concerns keeping the stock under pressure.
We see value in NIC below 60c but it’s unlikely to figure in one of our portfolios in the near future, given Indonesia’s heavy influence in the Nickel market.