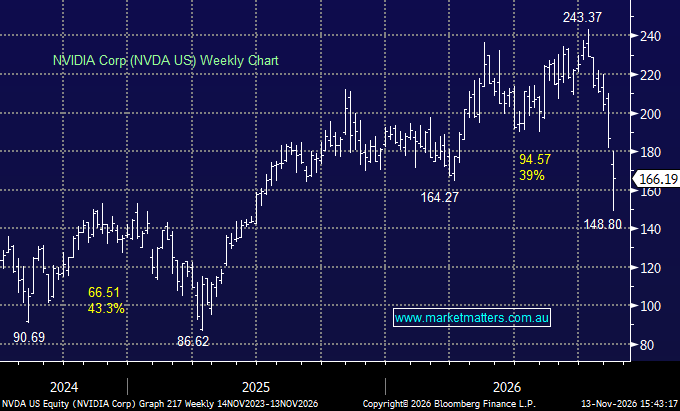
We are taking a position in Nvidia after a tumultuous few weeks for the business. Despite Jensen Huang being stood down, Nvidia’s long-term success rests on more than one individual. The stock has corrected ~40% from mid-October and now trades around 2 standard deviations, ~66%, below its historical P/E multiple. With consensus earnings CAGR of around 51% through to 2030, the current valuation offers an attractive entry point.
MM is buying NVDA US in the International Equities Portfolio, allocating 3% around $165
Add To Hit List

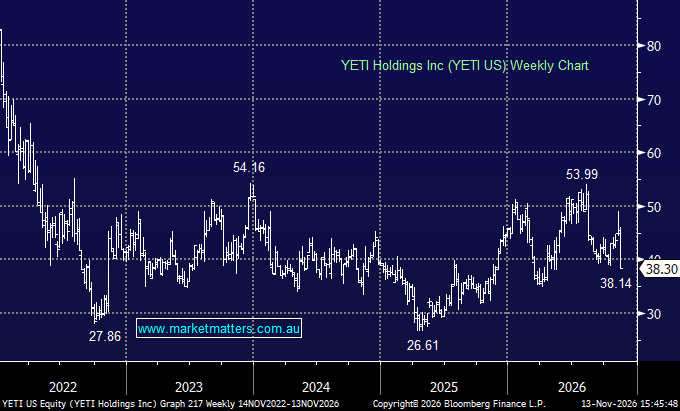
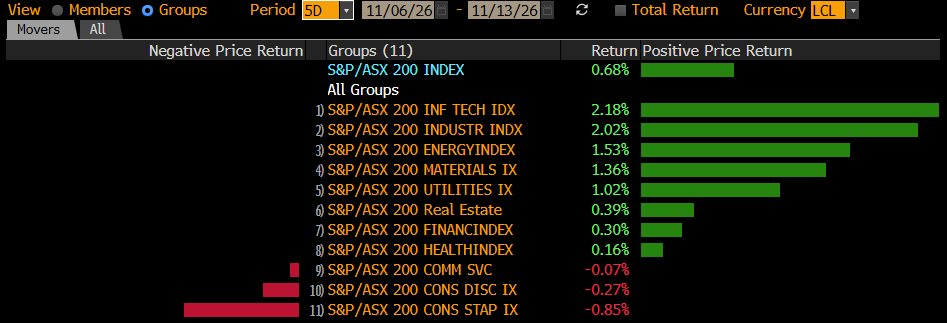
We are selling YETI after a second consecutive disappointing earnings result overnight. We trimmed our exposure back in August, however the consumer environment has softened since then. With US interest rates now expected to remain higher for longer, the near-term outlook for consumer discretionary, particularly YETI’s premium product offering, looks increasingly challenging. We are reallocating the proceeds to technology which has stronger structural growth drivers and less exposure to cyclical demand.
MM is selling YETI US in the International Equities Portfolio, breaking even ~$US38
Add To Hit List