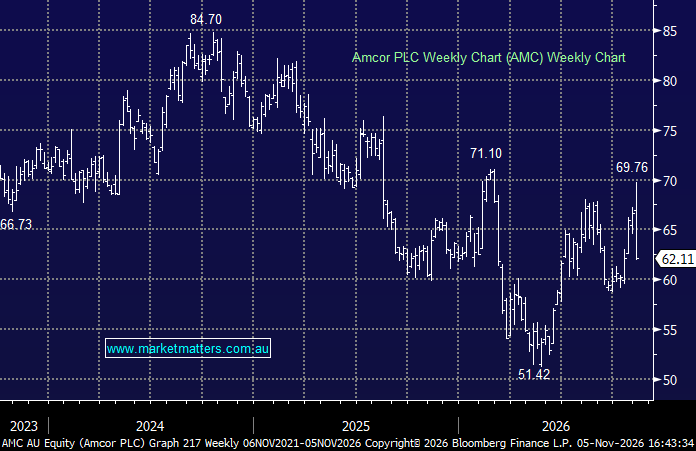
AMC –7.79%: Fell after delivering a mixed September-quarter result, with sales ahead of expectations but earnings slightly light and, more importantly, management cutting its near-term EPS guidance as higher energy and distribution costs bite.
Key Q1 highlights:
- Net sales: US$6.13bn, up 7% YoY and ahead of expectations.
- Adjusted EPS: US$0.95 vs US$0.99 expected and US$0.97 a year ago.
- Adjusted EBITDA: US$883m, broadly flat YoY.
- Organic volume growth: +1%, including +3% across focus categories.
- Synergy delivery remains on track toward Amcor’s US$650m three-year target.
- Quarterly dividend declared at US$0.66 per share.
The key negative was guidance. Amcor cut adjusted EPS expectations for the six-month transition period to US$1.70–1.80, from US$1.80–1.90 previously, reflecting delays in recovering higher energy and distribution costs through pricing.
That downgrade was the main reason for today’s sell-off, with the new guidance roughly ~ 5% below the previous range and around 11% below consensus at the midpoint for the December quarter.
Free cash flow was also weaker, leaving leverage elevated at around 3.8x. We’ve written about AMC’s leverage before (here), and todays update did nothing to allay some of these concerns.
That said, management believes the cost pressures are temporary and expects pricing actions to offset them, with no ongoing impact to 2027 earnings. Volumes are also holding up pretty well, which is encouraging given the softer global economic backdrop.
On ~11x forward earnings with an attractive dividend yield, valuation is not demanding, but today’s downgrade is a clear incremental negative to our view, and we’ll see lowering of earnings expectations on the back of this.
MM is now neutral on AMC ~$63
Add To Hit List