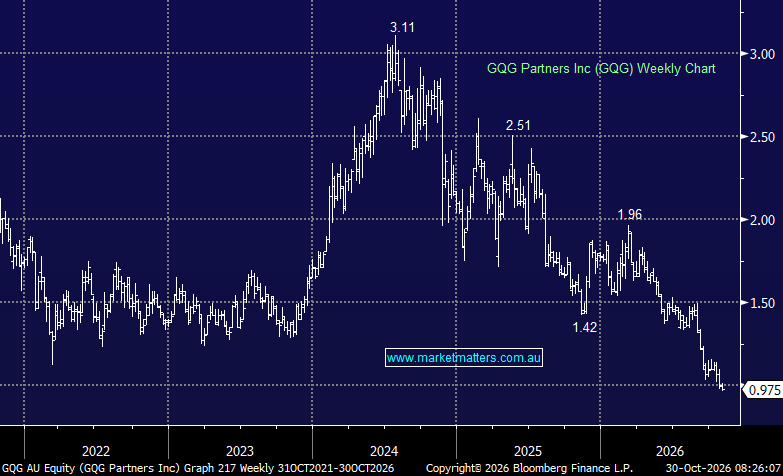
GQG has been a poor performer over recent months, with weak investment performance driving persistent outflows and heaping pressure on the share price. We had been prepared to give GQG the benefit of the doubt for two reasons: 1. Its attractive dividend yield, and 2. Its differentiated positioning away from technology, which provided something of a hedge against the risk of the tech trade failing to live up to increasingly lofty expectations.
However, GQG has subsequently pivoted its positioning, buying back into large-cap technology stocks, potentially at the wrong time. Time will tell whether this proves to be a prudent move, but we’re not convinced it will be enough to stem the outflows. With our original investment thesis failing, we are cutting our exposure across both portfolios, having previously held a 5% target weighting in the Growth Portfolio and 3% in the Income Portfolio.
MM is selling GQG in both the Active Growth & Income Portfolios, taking a loss ~98c
Add To Hit List