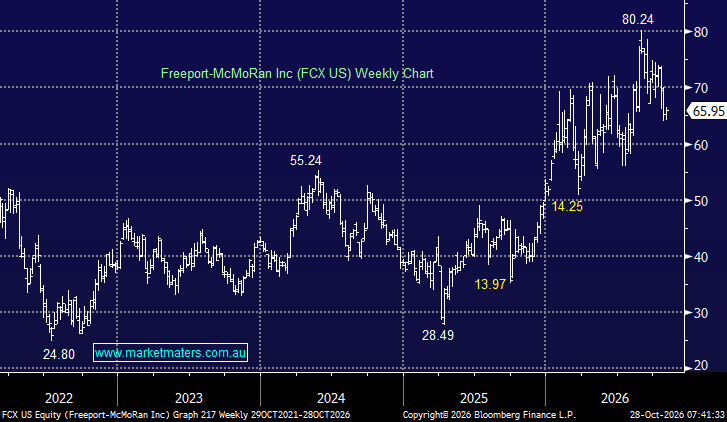
Freeport-McMoRan (FCX) finished +1.2% higher overnight after delivering a better-than-expected third-quarter result, with strong copper pricing offsetting softer volumes. The result itself was solid, although another trim to near-term copper sales guidance and higher capex continue to temper enthusiasm.
Key Q3 highlights:
- Adjusted EPS: US$0.88 vs US$0.81 expected.
- Revenue: US$7.55bn, up 8.2% YoY vs US$7.29bn expected.
- Copper production: 832mlb, down 8.8% YoY.
- Realised copper price: US$6.54/lb, up 40% YoY.
- Copper unit cash costs: US$2.07/lb.
- FY26 copper sales guidance cut to 3.0bn lbs from 3.1bn lbs.
- FY26 capex lifted to US$4.4bn from US$4.3bn.
The key issue remains Grasberg. The restart is progressing broadly to plan, but fourth-quarter copper sales have been cut to around 875mlb from 940mlb, with some variability expected between production and sales until processing facilities return to normal operating rates. Management still expects a meaningful recovery, with copper sales rising to 3.7bn lbs in 2027 and more than 4bn lbs in 2028.
More broadly, FCX remains very constructive on copper. Chairman Richard Adkerson summed it up simply: “The world requires a lot more copper and supplies are challenged.” Electrification, data centres and power infrastructure are driving structurally higher demand at the same time as new supply is becoming increasingly difficult and expensive to bring online. FCX expects its own copper sales to rise by more than 20% in 2027 and another 10% in 2028, with a pathway toward annual production of 4.5–5bn lbs around 2030.
The other area of focus for us is capital intensity. FCX now expects around US$5.2bn of capex in 2027, while the potential Bagdad expansion in Arizona is now estimated to cost around US$4.5bn, up from US$3.5bn previously. Rising energy, equipment and development costs are clearly eating into some of the benefit from higher copper prices.
We continue to like FCX as a high-quality way to gain exposure to a structurally tight copper market. Near-term execution has been messy, with softer volumes and rising capex, but the longer-term setup remains attractive. If Grasberg ramps as expected and FCX can deliver its projected production growth into 2027–28, it should be very well placed to benefit from a copper market where demand continues to rise and new supply remains difficult to find.
MM remains long & bullish FCX ~$US65
Add To Hit List