Copper and Resources
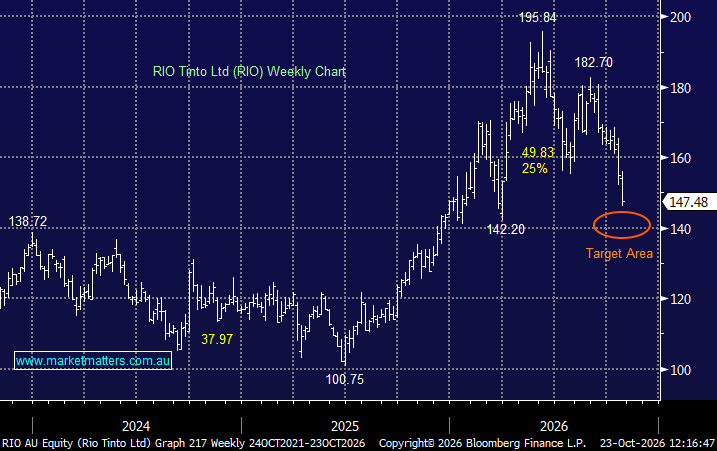
Hi Guys Thanks as always for your service. Quick question for you on resources. Has your view on allocations to this space altered at all recently given some of the softer data we are starting to see come through? Appreciate your thoughts. Cheers Tim Hi James and Team You bought RIO on Friday - If you already own RIO and BHP would you add to your RIO holding or consider Glencore instead? If so at what price? regards Debbie Copper forecast. I see you recommend Rio and I also was thinking likewise. But then I read this. It relates to a huge buildup in US copper inventories Copper has flowed into the US at a rapid pace over the past year. Inventories have now reached 1.5–2 million tonnes, depending on the source. Either way, that is a record high, particularly relative to the rest of the world. The copper stockpile has built up amid US President Donald Trump’s threat to impose tariffs on refined copper, although a decision has been delayed until 2027. One fear lingering in the market now is that Trump won’t impose tariffs, and suddenly the US finds itself awash in copper … way beyond what it needs. That could, in one scenario, cause the price of copper to drop sharply, possibly as much as 20%. You should care because, odds are, your super fund has significant exposure to BHP Group (ASX:BHP), which is increasingly trading as a copper stock. Picture2 Copper’s price trajectory matters. Shares in BHP and Rio Tinto (ASX:RIO) have shown some jitters in recent trading. That said, copper on the US COMEX exchange is currently in what’s known as ‘contango’, where futures prices are higher than spot prices. That means there’s profit in buying copper now, storing it, and delivering it at a later date. It’s why one analyst said recently, in response to fears of an inventory-led copper price drop, that “[storage] economics are now sufficient to keep the metal tied up”. Copper is, of course, also highly correlated to economic growth. That remains on track, for the moment. There’s also no visible slowdown yet in the level of capex spending from the US hyperscalers — the primary narrative behind copper these days, despite data centres only being about 4% of current demand. Meta Platforms (NASDAQ:META) released its third-quarter earnings this week and lifted its capital spending guidance higher again, for the third time this year. Overall, I suspect copper prices are unlikely to fall sharply, at least for the rest of this year. It’s something for our North American neighbours to mull over by the fire — if the government lets them have one. Best wishes, Callum what do you think of this assessment?