Hi Simon,
We think it is important in this environment to distinguish between different parts of the private credit market. Private credit is a very broad asset class, and the risk profile of a diversified, asset-backed credit portfolio can look very different from more concentrated property backed exposures.
MA2HA has no direct real estate lending exposure, and we think it genuinely has a diversified underlying portfolio, with ~85% of the portfolio in Asset Backed Lending and 15% Direct Corporate Lending, across 137 investment positions and 81 channel partners and issuers.
Diversification is important in credit because upside is contractually capped while downside is not. MA2HA’s Asset Backed Lending exposure adds another layer of diversification because individual facilities can themselves comprise hundreds or thousands of underlying loans or receivables. This is different to say MXT which is more direct lending.
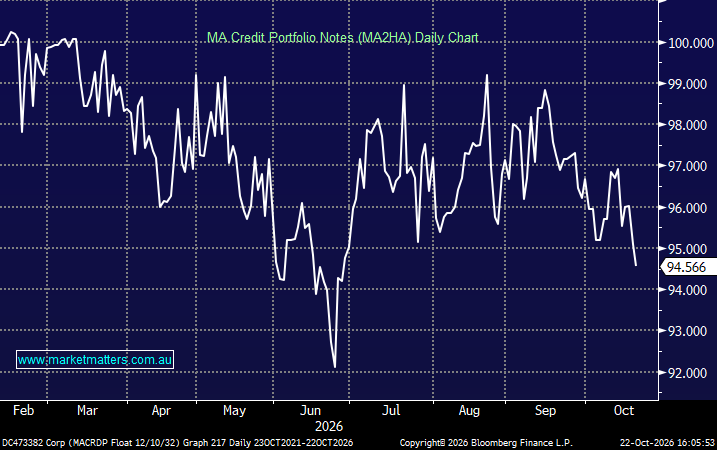
It also has some protective features like a 5% first-loss capital buffer, offering some protection against credit losses, although this is not a capital guarantee. The notes mature in December 2032, but with an expected call date in December 2031. Being a note with a maturity date should mean they trade better in times of stress than an LIT with no call date, and we’re seeing that at the moment, although pretty much all of the sector is under some pressure.
Overall, we think MA2HA is a solid security.