Hi Tracy,
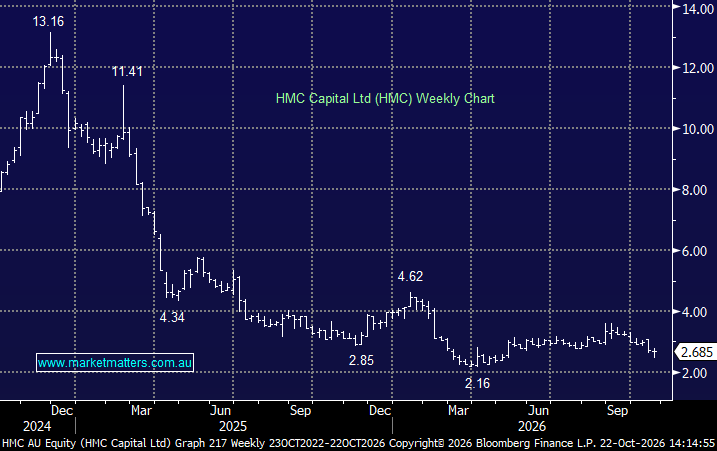
HMC Capital Ltd (ASX: HMC): we last discussed HMC here after its strong FY26 result and FY27 outlook. HMC is trying to evolve into a larger, more diversified asset manager and the 23% growth in management fees caught our eye.
However, HMC has drifted ~20% since its August result given the sectors they operate in are under a decent amount of pressure i.e. digital infrastructure, private credit and real-estate valuations have been hit. While FY26 operating EPS of 40.4c met guidance, the result benefited from non-cash valuation gains that will be excluded from FY27 reporting. Consequently, FY27 underlying EPS guidance of 35c appears to represent a decline, although it implies 16% growth on a like-for-like basis.
Ultimately, we believe the longer-term growth story remains appealing, but execution is now the key. HMC has flagged a ~$5bn investment pipeline across private credit, real estate and digital infrastructure, although converting this into fee-generating assets is taking longer than we had hoped. The shift towards institutional investors should support more sustainable growth, but also extends the time required to secure new capital.
- We believe HMC offers plenty of upside from here, but it’s a medium-term turnaround opportunity, operating in an area with plenty of current headwinds.
Lifestyle Communities (ASX: LIC): Directors (insiders) buying their own stock is a good leading indicator on performance, and with LIC trading down more than 80% from its 2021 high we can see why it caught your attention.
LIC Chairman David Blight purchased 51,587 shares on-market at $3.87 on 13 October, investing ~$200,000 to more than double his holding to 101,587 shares, with the stock trading near nine-year lows – a vote of confidence, although the regulatory uncertainty surrounding VCAT’s adverse ruling on resale-based fees remains a significant hurdle, and creates a lot of unknowns for the company.
- We think LIC looks interesting around $3.90 as an aggressive play, almost trade from a risk/reward perspective, but wouldn’t give the position too much room.