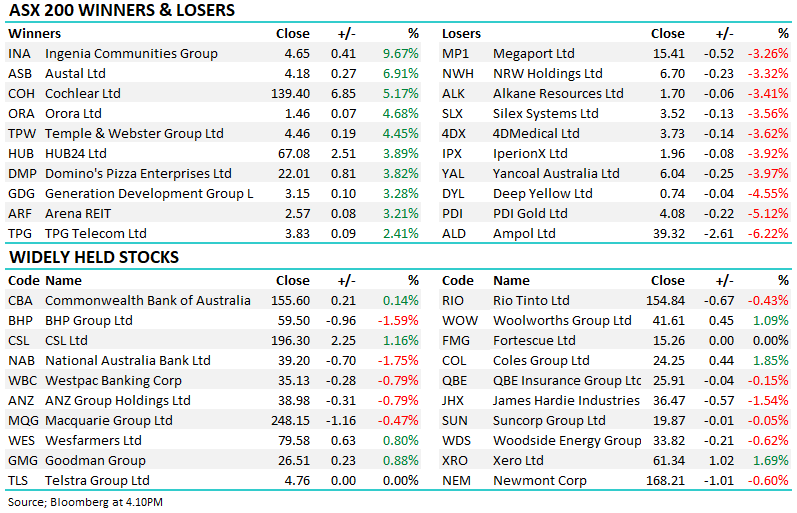
Ramelius Resources (RMS) has the strongest daily return correlation with gold over the past 12 months at 0.34, narrowly ahead of Newmont (NEM) at 0.337. However, correlations across the sector remain relatively modest, with even the highest reading suggesting that gold prices explain only part of the day-to-day share price movements. Operational execution clearly has a big influence on returns. Northern Star (NST), despite being one of the ASX’s largest gold miners by market capitalisation, has the lowest correlation in the group at 0.20.
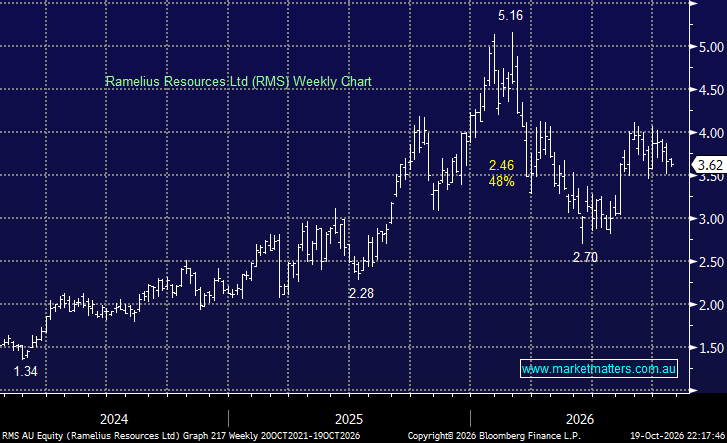
RMS is down ~13% year-to-date, significantly underperforming gold, which is off ~4%. The weakness is a result of lower production which has pushed up costs, plus they were impacted by gold hedging during a period of strong prices. The company reported a first-half net loss of $11.7 million, while FY26 net income fell 75% year-on-year to $118.8 million. Shares dropped from their January highs to a 52-week low of $2.70 in June.
- Sentiment has since improved, supported by the company’s FY27–FY30 growth plan, which targets annual production of 560,000–610,000 ounces by FY30.
The obvious question is whether Ramelius can deliver this expansion while managing costs and capital expenditure, with the benefits of higher production expected to take time to translate into stronger free cash flow. However, we believe RMS is offering compelling valuation of around $3.50, with the bulk of production unhedged, with only modest collar and put option protection in place during the high-capex growth phase.
- We like the risk/reward towards RMS around $3.50 support.
MM is bullish towards RMS around $3.50
Add To Hit List