Hi Steve,
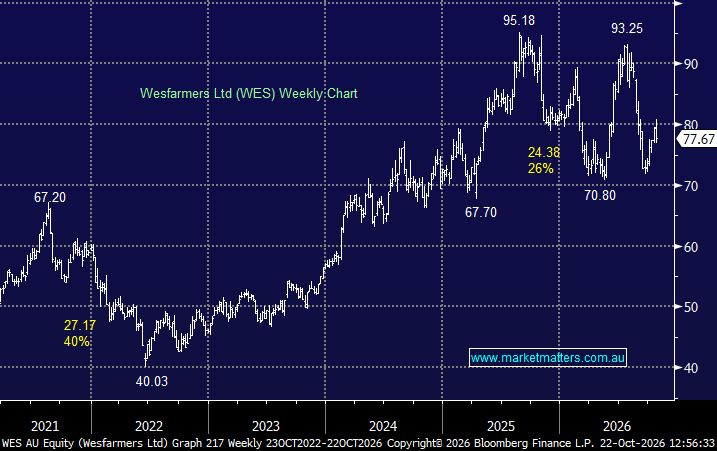
We have considered WES over recent months but was removed from the hitlist (Growth Portfolio) when we bought back into JBH. From an analyst perspective views are very mixed:
- 2 Strong Sell, 4 Sell, 3 Holds and 5 Buys – we could call it a net sell but only just.
We last wrote about WES after their FY26 result in August here, and it remains a quality business, their result offered little to get excited about. Bunnings continues to deliver, Kmart remains resilient and Health is gaining traction, but with EBIT growth of just 0.6%, rising capex and Mt Holland still consuming cash, the premium valuation looks difficult to justify and therein lies the issue.
- The “safety” bid WES has enjoyed in the current uncertain times has the stock trading on the rich side compared to its long-term valuation.
MM likes the business, but we’d need either a cheaper entry point or stronger earnings growth to become more enthusiastic, as it is today, closer to $70 would have us more interested.
Conversely JB Hi-Fi (JBH) has fallen almost 50% from its inflated 2025 high valuation returning some value to the well-known brand trading around $71 the stock is ~17% below its average P/E.
In essence we believe an almost “worst case” scenario is being built into interest rates and the Australian consumer leaving plenty of upside form here although we caution, we did use the word” almost.”