Hi Carl,
The reputational damage is significant at a time when the blow torch is being applied to private credit more generally – particularly property backed private credit.
No one likes being locked in funds (which is the case with several Metrics wholesale funds) and obviously the suspension playing out across their listed vehicles means investors are currently locked in there.
In terms of how the LITs will trade when they come back, this is a tougher question. Our gut feel is they may get hit hard initially, before bouncing back, but this will be dependent on the quantum of NTA recuts. It seems like FY26 is largely agreed here, with smaller revaluations lower than we thought may have played out – it’s more a case of re-stating/tidying up prior years, and then obviously the question around how assets were valued in the past.
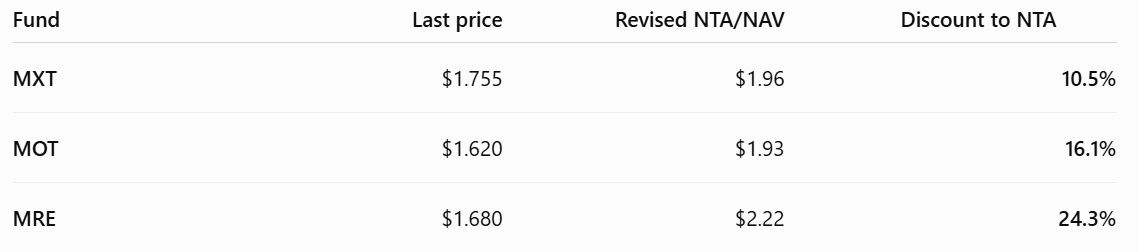
In the latest update, MXT’s current NTA was only cut about 2%, whereas the higher risk MOT was cut about 10% and MRE about 12%; yet the listed-market discounts were already materially wider than those accounting adjustments. In particular, MRE at ~$1.68 versus $2.22 revised NTA is implying another ~54c/unit below the revised valuation.
If these funds are hit further when they come back online, we will be assessing them carefully for opportunities. The market often overshoots to the downside in these sorts of scenarios, and we actually think this process could provide more confidence around underlying asset valuations.
This is a situation we are watching carefully. We have no exposure to Metrics currently, having sold out several years ago on concerns that are now coming to the fore.