Hi Ian,
Firstly, let’s look at the two utilities individually:
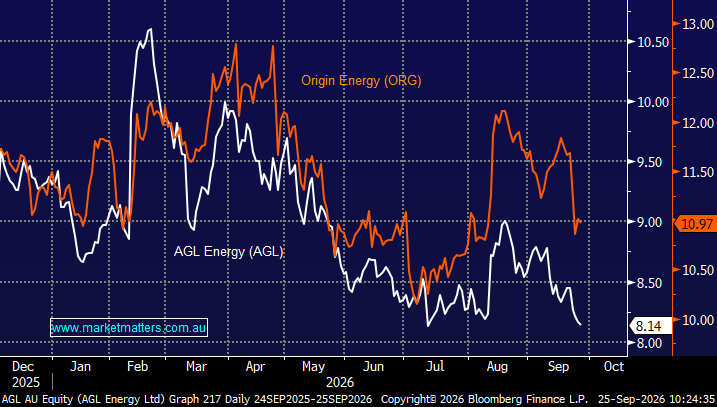
AGL Energy (AGL) delivered a solid FY26 result covered here, while earnings remain under pressure, as legacy gas contracts roll off and electricity prices normalise, strong cash flow, lower costs and an attractive dividend profile provide support. Following a period of significant earnings downgrades, the stock is now looking attractive ~$8, helped by its forecast +6.2% fully franked yield.
- MM currently holds AGL in its Income Portfolio.
Origin Energy (ORG) was covered in detail by MM earlier this month here, our conclusion was along the lines of:
- We can see ORG making new highs into 2027, helped by its forecast +5.5% fully franked yield and at the time we added ORG to our Hitlist.
AGL offers the stronger income proposition, while also trading on a cheaper valuation. In terms of growth, while neither looks exciting in the near-term ORG Origin trades at a premium reflecting its energy-transition strategy and LNG optionality, although consensus FY27 estimates are yet to show a meaningful growth advantage.
Hence, we like both, our preference is a bit harder but without sitting on the fence we prefer AGL for yield and ORG for growth.