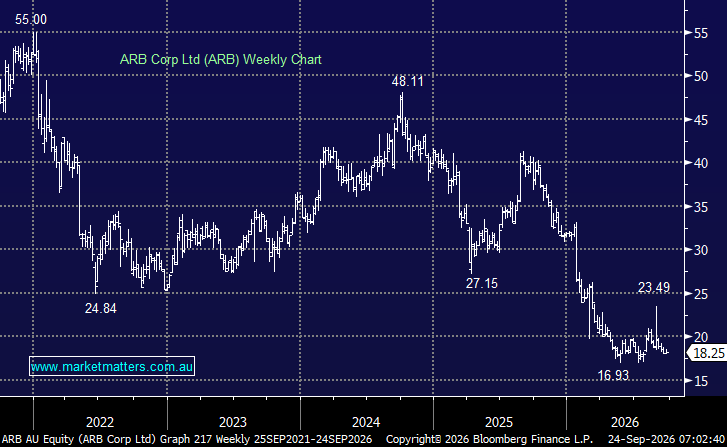
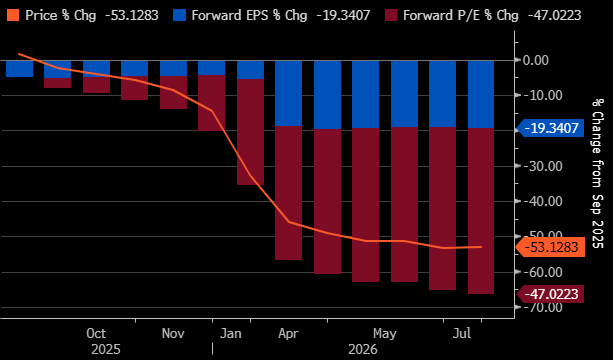
ARB surged following its FY26 result, and optimistic FY27 outlook, covered here, though bearishness quickly resumed – the share price has more than halved over the last two years. The stock has endured a brutal 12 months, materially underperforming both the ASX 200 and Consumer Discretionary sector (-19.5%). The decline has been driven by a combination of weaker 4×4 vehicle sales, January’s profit warning and a significant reset in earnings expectations, with forward EPS falling around 39% from $1.37 to $0.84. At the same time, investors have become far less willing to pay a premium for those earnings, with ARB’s forward P/E contracting from around 29x to 18x—a painful combination of earnings downgrades and multiple compression.
- The 12-month decline was driven by roughly equal contributions from EPS cuts and P/E compression.
chart

ARB Corp (ARB) – Price vs EPS & Forward P/E % change – Source: Bloomberg
chart
ARB Corp (ARB) – Price vs EPS & Forward P/E % change – Source: Bloomberg
As we touched on before there have been some tentative signs of improvement, with ARB’s FY26 result better than feared, with 2H profit before tax returning to modest growth after a difficult first half, while improved Toyota vehicle supply should provide some support into FY27. However, OEM sales fell 27% in FY26, and earnings expectations were cut further following the result, quickly unwinding much of the initial +14% relief rally. After such a dramatic de-rating, expectations are clearly much lower, and ARB now needs improving vehicle volumes and a sustained recovery in earnings to demonstrate that the worst is behind it.
With ARB trading more than 30% below its 2-year valuation metrics, there is clear room for a turnaround for this distributor of 4×4 accessories and off-road equipment.
- We like the risk/reward into new lows around $16.50, for a potential sharp 40% rally – we hold ARB in our Emerging Companies Portfolio.
MM is bullish towards ARB around $16.50
Add To Hit List