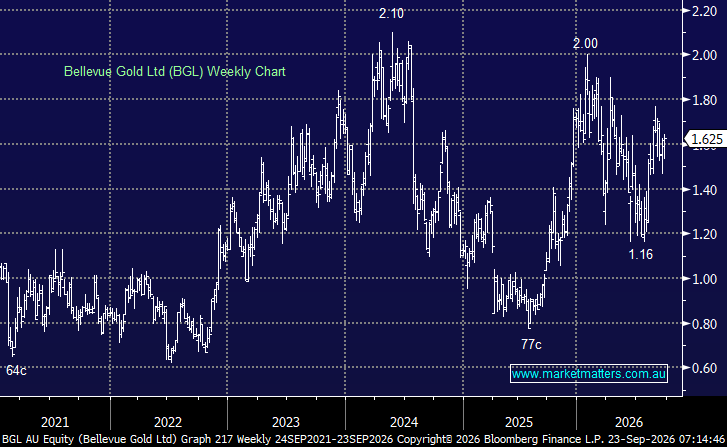
Bellevue Gold (BGL) delivered a much-improved FY26 result yesterday, but the numbers again highlight just how costly its legacy hedge book has been during one of the strongest gold markets on record. The encouraging part is that the end of this issue is now coming into sight.
FY26 numbers:
- Revenue of A$576.3 million, up 46% year-on-year.
- EBITDA of A$237.5 million, representing a healthy 41% margin.
- Net profit of A$7.1 million, versus a loss of A$45.9 million last year and ahead of consensus of ~A$3.2 million.
- Operating cash flow of A$252.9 million.
- Free cash flow of A$62.6 million, after all hedge deliveries.
- Gold production of 143,500oz, within the 130,000–150,000oz guidance range.
- AISC of A$2,827/oz.
On the surface, a A$7 million profit from a $2.4bn gold miner in this environment is underwhelming, but that’s a direct result of their pesky hedge book. Bellevue delivered 83,400oz into hedges during FY26 at prices materially below spot, with management estimating NPAT would have been around A$205 million without the impact of those commitments. Revenue would also have been roughly A$285 million higher if all production had been sold at the average spot price achieved during the year.
That is a clearly a huge opportunity cost, but importantly it is now finite. Bellevue still has around 68,650oz to deliver under forward sales over the next two years at an average price of approximately A$3,004/oz, well below current spot gold of ~A$6000. However, the company is looking to accelerate deliveries and expects to close out the hedge book during FY27, which would finally give us much greater exposure to the prevailing gold price.
Operationally, management has retained FY27 guidance for:
- Production of 150,000–170,000oz.
- AISC of A$2,800–3,100/oz.
- Non-sustaining capex of A$90–100 million.
- Exploration expenditure of A$25–30 million.
Management also expects production to become more consistent through the year, which is important given Bellevue has yet to deliver the production profile initially envisaged when the mine was developed.
The share price gained ~4% following the result, which makes sense to us. The headline earnings beat was solid, but the more important development is the improving visibility around the balance sheet and the gradual removal of the hedge overhang.
MM’s view: We own BGL and continue to think the investment case improves materially once the hedge book disappears. FY26 demonstrated that the mine can generate strong EBITDA and cash flow, but shareholders have still been denied much of the benefit from the gold price because of legacy hedging. The next leg of the story is all about execution: lifting production consistency, controlling costs and clearing the remaining hedge commitments without damaging the balance sheet. If Bellevue can achieve that through FY27, the earnings profile should look very different with substantially greater exposure to spot gold prices.
MM remains long & bullish BGL
Add To Hit List