Hi Richard,
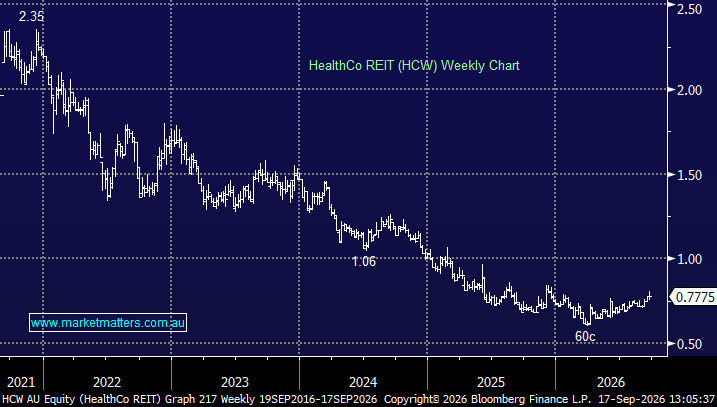
The situation at HealthCo Healthcare & Wellness REIT (HCW) is clearly improving, but it hasn’t yet been fully resolved. Terms have been agreed with alternative operators for the 10 remaining Healthscope hospitals, although these arrangements remain subject to receiver and lender approvals, with completion targeted for 1H FY27.
Importantly, as you highlight, the underlying portfolio continues to perform well: HCW has collected 100% of rent through August, occupancy remains ~99%, and NTA stood at $1.35 per unit at June 2026.
- This week, lenders backed the transfer of 10 hospitals to alternative operators, although final approvals remain outstanding.
The key outstanding issue is distributions, which remain paused until the Healthscope transition is completed. HCW has flagged FY27 distributions of 6.0c per unit, but this remains conditional on successfully resolving the situation. At around 75–76c, the stock is trading at a substantial ~44% discount to NTA, suggesting the market continues to price in considerable uncertainty.
- Three directors have bought ~$50k worth of stock this month, better than selling but not meaningful, plus these were made under HCW’s voluntary non-executive director unit acquisition arrangement, hence we wouldn’t characterise them as conventional discretionary insider buying.
The attraction here is the disconnect between HCW’s improving operational position and its deeply discounted valuation. 100% rent collection, 99% occupancy and agreed terms with replacement operators suggest the Healthscope risk is steadily being reduced, but final approvals and the resumption of distributions remain important hurdles.
- The discount to NTA provides some compensation for that uncertainty, making the formal resolution of Healthscope and reinstatement of distributions the key potential catalysts for a meaningful re-rating.
We like the risk/reward towards HCW around 75c, but it doesn’t come without risk.