Why Cleanaway Waste (ASX: CWY) is up more than 3%
Cleanaway Waste Management (CWY) is trading more than 3% higher today after confirming that EQT Infrastructure remains committed to acquiring 100% of the company at no less than its previously indicated offer price, following its due diligence review. The update is an important step towards a potential transaction and has increased confidence that EQT intends to proceed with its approach. As a reminder:
- In August EQT Infrastructure has made a non-binding, all-cash proposal of $3.13 per share for Cleanaway, having improved its initial approach.
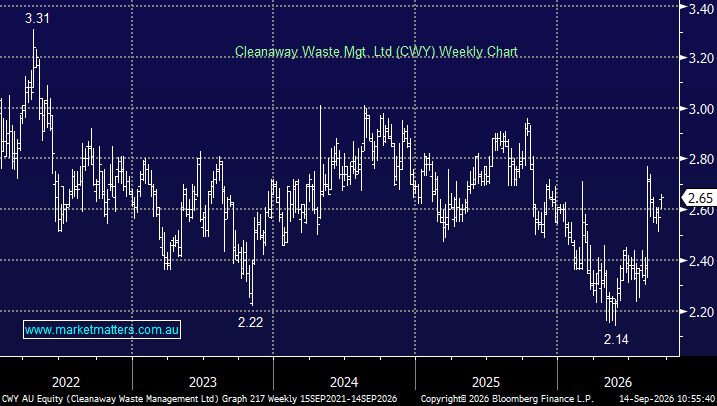
The offer implies an EV/FY26 EBIT multiple of around 20x and, with CWY trading at around $2.65, represents roughly 18% potential upside from current levels.
The $3.13 offer is subject to adjustment for any dividends or distributions paid by Cleanaway, while the proposed structure also allows for a fully franked special dividend. The latter could improve the after-tax outcome for eligible Australian shareholders, although any cash component would reduce the headline offer price accordingly.
Cleanaway and EQT initially entered into a Transaction Process Deed, providing EQT with up to nine weeks of exclusive due diligence while the parties worked towards negotiating a binding Scheme Implementation Deed. Importantly, Cleanaway’s Board has indicated it intends to recommend the $3.13 proposal, subject to EQT completing confirmatory due diligence, submitting a binding offer on terms no less favourable than the current proposal and the parties executing an implementation deed.
Today’s update is encouraging on this front. While the hard-exclusivity period has now expired, EQT has confirmed it remains committed to pursuing the acquisition at no less than $3.13 per share and is continuing confirmatory due diligence as the two parties work towards finalising an implementation deed.
At $2.65, CWY is still trading around 15% below the $3.13 offer price, highlighting the uncertainty that remains. The proposal is still non-binding and there is no guarantee a transaction will ultimately be agreed or completed. However, we like the risk/reward towards CWY below $2.70.
- Today’s update is clearly positive and increases our confidence that the deal will proceed, particularly given EQT has reaffirmed its commitment after conducting due diligence.
However, the sizeable discount to the $3.13 offer shows the market is still pricing in meaningful execution risk until a binding Scheme Implementation Deed is signed.