Skip to Content
scroll

Thoughts on Regal Partners (ASX: RPL) and Metcash (ASX: MTS)

Our Q&As are emailed in our Saturday Morning Report, find the answer to this question below.

The Latest Q&A

Question asked

Thoughts on Regal Partners (ASX: RPL) and Metcash (ASX: MTS)

Esteemed team, Please forgive me for asking 2 questions. My excuse is that the chaos in the market has overwhelmed me and that you have recently commented on both of these stocks so there should be little research effort needed on your part. A while ago I asked about MTS and expressed concern that it was a small company pitted against giants which does not auger well when a possible recession is in the air. You replied that if you added the various divisions of MTS together that they were , in fact, a big company. Yes, this is so . However, the DIVISIONS of MTS are small compared to the corresponding divisions of their larger corporate competitors. The hardware arm of MTS is very small compared to Bunnings. The supermarket arm of MTS is very small compared to Woolworths or Coles or Aldi. The company is down a good bit from it's highs and yet you still keep it in your income portfolio. Are you happy with this decision and if so, why? And should a recession hit us how do you think it will fare against it's larger opponents? You said RPL , which is in your Emerging Companies' portfolio is a good company but there are a number of red flags and you would hold off on buying more until you saw some improvement. It seems most market pundits are pretty optimistic about it and feel it's present low price might well be a buying opportunity. Has you view changed at all or do you still think the risk/reward situation is still not where you want it to be? If there were a recession is it likely that the company would survive and ultimately thrive. With people like Charlie Aitken on board they should do pretty well. It is said that the quality of a company's management is often more important than the credit usually given to that asset. Having said that it is often very difficult to judge the quality of a company's management accurately. I appreciate and greatly respect the opinions and ideas you provide. Having said that; NO ONE gets it right all the time and conditions change constantly ___especially these days. That is why I am revisiting these companies. Thanx again, Octogenarian
Answer

Hi Octogenarian,

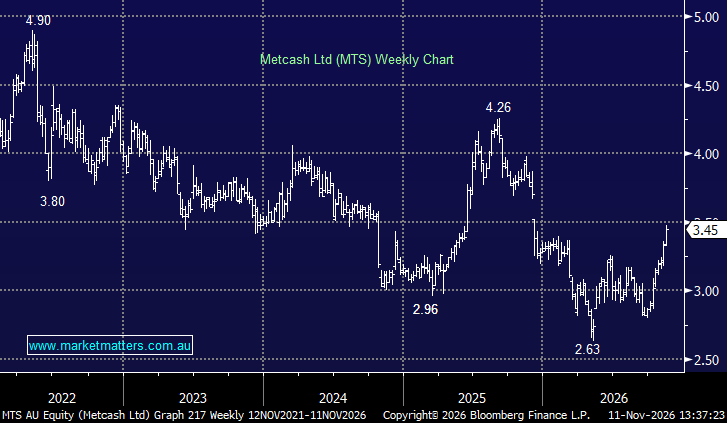
Metcash (MTS) – MTS has significantly outperformed the ASX 200 in 2026 and has also outperformed its major supermarket peers over the past three months, gaining +10% compared to Woolworths (WOW) at +4% and Coles (COL) at -6%. Of course, performance depends on the timeframe, with WOW undoubtedly the standout over more recent periods as it takes market share from COL.

As you mentioned, we hold MTS in our Income Portfolio, with its fully franked yield of ~5.2% comparing favourably to WOW (2.4%) and COL (3.6%). It remains our preferred pick across the sector for a combination of yield, value and growth potential.

In terms of strategy, MTS, through its IGA network, offers a differentiated approach to convenience retailing, and we genuinely think they do a very good job of it. Many of its franchise stores occupy high-value locations, providing a service that we would argue actually improves the communities in which they operate.

The valuation gap between MTS and the majors reflects the very issue you’ve raised, with MTS trading on ~13x earnings versus COL at ~23x and WOW at ~27x. You’re right that smaller scale generally means higher costs, but MTS has demonstrated it can compete effectively by offering a compelling alternative for shoppers who value convenience over price.

Ultimately, we believe IGA/Metcash has carved out a sustainable niche that allows it to coexist with the majors, rather than compete head-on. It’s a similar strategy being pursued across its hardware and tools businesses.

Our original investment thesis centred on the valuation discount narrowing, and we still believe that argument holds. We’ve therefore retained our position, which has generated around 8% p.a. since purchase, or ~40% overall.

In a recession, we suspect MTS would be somewhat less defensive than the major supermarkets, although consumer staples generally tend to outperform the broader market during periods of economic weakness.

Regal Partners (RPL) – We know Charlie well. He’s a good operator and even spoke at a Sydney Market Matters event a few years ago, although importantly, he’s not the person managing the portfolios.

When assessing fund managers, alternative or otherwise, the most important metric is almost always investment performance, and this is where RPL has struggled recently.

  • Regal’s flagship Long/Short Fund declined -18.9% in the 12 months to September 2026, underperforming the ASX 300 Accumulation Index by a substantial 21.28%.

An improvement in returns is pivotal for RPL, particularly with the planned retirement of Phil King. Ultimately, funds follow performance.

Historically, Regal has demonstrated an ability to bounce back from periods of underperformance, which means advisers who understand the investment process are generally less inclined to withdraw funds at cyclical lows. However, the longer poor performance persists, the greater the risk of meaningful outflows.

One of our team recently met with a Regal portfolio manager, and the discussion didn’t leave us with the same level of confidence we’ve had following previous meetings. That has contributed to our more cautious stance.

For now, we’d classify RPL as more of a hold than a buy, with a sustained improvement in investment performance needed to rebuild our conviction.

Finally, in a recessionary environment, fund managers generally face a difficult backdrop, as falling asset prices, weaker performance and potential redemptions can combine to put pressure on earnings.

chart
image description
Metcash Ltd (MTS)
image description

Relevant suggested news and content from the site

Back to top








