Hi David,
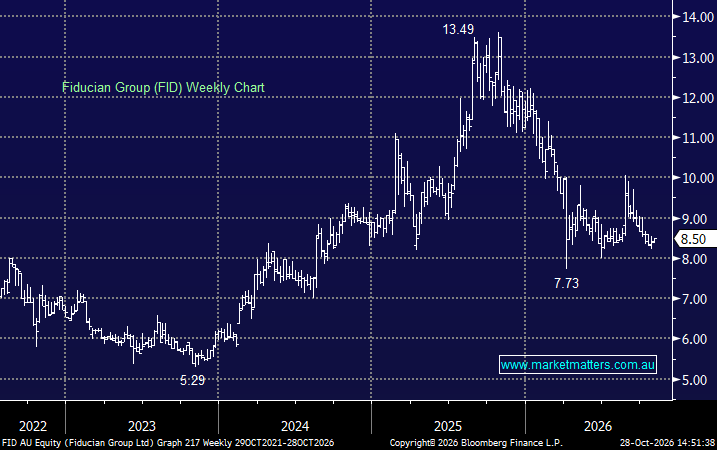
Fiducian Group (ASX: FID) has fallen by more than 40% from its 2025 high more than offsetting the ~6.3% fully franked yield, significantly underperforming the broader financial sector in 2026, due to a series of regulatory setbacks.
- The most significant was ASIC’s legal action against subsidiary Fiducian Investment Management Services over allegedly misleading ESG claims relating to its Diversified Social Aspirations Fund.
In March, Fiducian agreed to pay a $7.3m penalty plus $650,000 in legal costs, with the settlement formally approved by the NSW Supreme Court in August. Compounding the pressure, APRA imposed additional licence conditions on the trustee of Fiducian’s superannuation fund in April, citing weaknesses in investment governance, strategic planning and member outcomes.
- The double regulatory blow sent the stock down towards its lowest level in almost two years.
Slowing fund inflows and a less supportive interest-rate environment have added to the pressure. Net inflows from Fiducian’s aligned adviser network fell to $45m in the March quarter, compared with $59m a year earlier, while legacy independent advisers recorded $17m in net outflows. These trends raise concerns about future funds under management (FUM) and fee growth.
Although the ASIC settlement removes some uncertainty, the ongoing APRA requirements and softer flows continue to cloud the outlook. Although at least it’s not expensive trading ~10x, almost 30% below its medium-term valuation.
- We would want to see clear evidence of a recovery in fund flows before considering FID ~$8.50.