Hi Tom,
Fair Isaac Corporation (NYSE: FICO) is a new stock to the MM report, for members unfamiliar with the company, it’s a technology / analytics software company, best known for creating the FICO Score, the dominant consumer credit-risk score used by US banks, mortgage lenders, credit-card companies and auto lenders. It also sells software that helps financial institutions automate lending decisions, manage customers, detect fraud and assess risk.
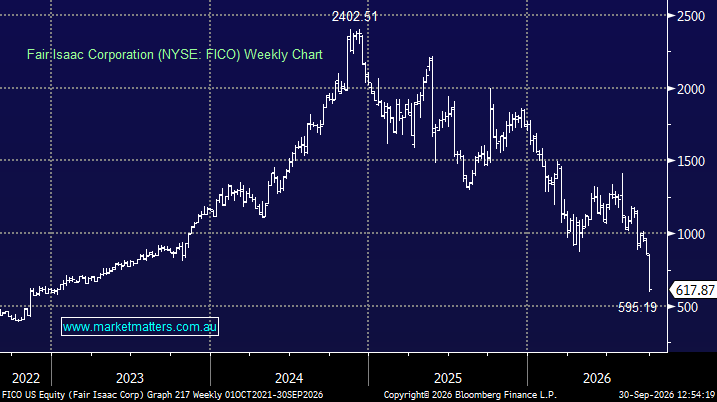
FICO has plunged ~26% this week after the US housing regulator moved to put rival VantageScore on equal footing with FICO for pricing mortgages backed by Fannie Mae and Freddie Mac. It’s a significant development because FICO’s Scores division generates around 68% of group revenue and has enjoyed extraordinary pricing power, with 3Q Scores revenue jumping 41% as higher mortgage pricing helped drive group revenue up 26% to US$674m and EPS up 41%.
The concern is that FICO’s effective monopoly in US mortgage credit scoring is being dismantled. Lenders will increasingly be able to use VantageScore rather than FICO when pricing conventional mortgages, potentially giving them greater bargaining power and making FICO’s aggressive price increases much harder to sustain. The bull case is that switching will take time given FICO is deeply embedded in lenders’ systems, while its non-mortgage scoring and fast-growing software platform remain largely unaffected.
- However, the market is now likely to apply a lower valuation to earnings previously regarded as exceptionally predictable.
To us this looks more like a genuine weakening of FICO’s moat than a temporary scare, particularly because pricing power has been central to its earnings growth. Following the sell-off, valuation has fallen dramatically and is ~70% below its 5-year average. The key question now is how much of its premium profitability can survive genuine competition.
Importantly before this week’s news the US$13.3bn stock had already more than halved from its 2025 high, i.e. the trend was down although revenue and eps were trending upwards.
- We see no reason to buy FICO here; it may bounce but its fundamental background has deteriorated badly making it simply “too hard.’