Hi Darren,
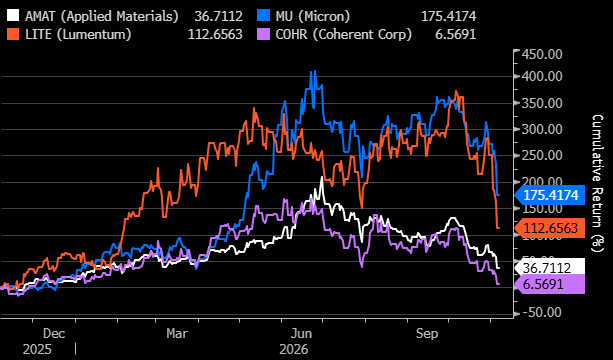
A very topical question as the “AI Trade” unwound this week after the Democrats swept the House and Senate, as was expected although you wouldn’t have thought so looking at stocks on Thursday night.
In terms of Applied Materials (AMAT US) we aren’t considering increasing our position for portfolio management/risk reasons, but we do like the sector into current weakness as we’ve alluded to through the week – in the past fortnight we forecast the Philadelphia Semiconductor Index (SOX) to break below the 10,000 area this week, which it did, hitting our extreme target of 9000 on Thursday night.
- We believe the risk/reward now favours the bulls in the AI Trade although the momentum is a touch scary!
Of the 4 stocks mentioned the numbers are looking increasingly attractive the deeper the correction becomes:
Micron Technology (NASDAQ: MU) stands out on valuation, profitability and earnings growth, trading on just 3.8x forward earnings and 3.4x EV/EBITDA, with forecast EPS growth of 131%. Its exceptional margins reflect the strength of the memory chip cycle, although the remarkably low valuation suggests investors remain wary of how sustainable current earnings will prove.
Lumentum (NASDAQ: LITE) offers similarly impressive growth, with forecast EPS increasing 133%, supported by accelerating demand for optical networking technology used in AI data centres. However, its higher valuation leaves less room for disappointment.
Coherent (NYSE: COHR) looks relatively inexpensive at 14.4x forward earnings, with forecast EPS growth of 97%, although weaker margins suggest its profitability recovery still has further to run.
Applied Materials (NASDAQ: AMAT) offers a different proposition, with a more established and diversified semiconductor equipment business, but less explosive growth. Trading on 17.9x forward earnings, with forecast EPS growth of 51%, AMAT appears relatively expensive compared with Micron, although its broader exposure to semiconductor manufacturing provides a different risk profile.
We like all 4 in current weakness but if we were to select an addition to AMAT it would be MICRON.