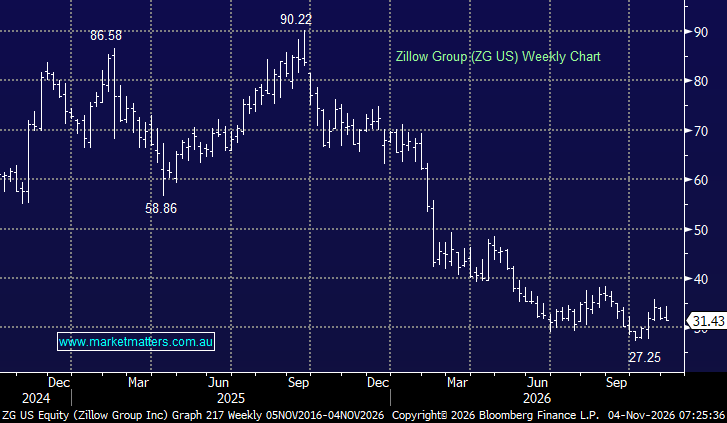
We have owned Zillow (ZG) previously, initially buying around US$46 in mid-2024 before exiting ~US$54.50 in February 2026, as the “SaaSpocalypse” gathered momentum and we chose to reduce exposure to higher-risk growth names amid a rapidly changing market backdrop. With Zillow now back around US$33, we are interested again.
The bottom line; we think the stock screens cheap relative to its likely earnings growth, even without assuming a strong recovery in US housing.
Consensus expects revenue to rise from ~US$2.9bn in FY26 to ~US$4.1bn by FY29, while adjusted EPS is forecast to more than double from roughly US$2.12 to US$4.66. Free cash flow is also expected to rise from around US$418m to almost US$900m, yet the stock is trading on only around 14x next-four-quarter earnings, 13x FY27 and 10x FY28. That is a very different proposition from the 30–40x earnings multiples it traded historically.
3Q earnings for Zillow are out tonight, so we’ll get updated numbers on how the platform is progressing, with consensus looking for quarterly revenue of US$753.5m and EPS of 59cps. Expectations for the 4Q sit at US$709m revenue and underlying earnings (EBITDA) of US$185m.
The key positive is that Zillow has continued to grow through one of the toughest US housing markets in decades. High mortgage rates have crushed turnover, yet Rentals remains a standout, with revenue expected to grow around 30%, while Mortgages and other services are gradually reducing Zillow’s dependence on home sales.
The biggest strategic risk is Google, which has started testing property listings directly in search results. That is a credible threat to traffic and advertising economics, but we don’t think it is straightforward to replicate Zillow’s brand, agent relationships, consumer engagement and property data. The same dynamics are relevant to REA in Australia, however, we’re more cautious on REA simply because the competitive landscape has shifted since Domain was bought by CoStar in 2025, and they’ve got credible plans to eat into REA’s market share, with a significantly larger war chest than Domain had under Nine ownership.
With Zillow trading on such a depressed multiple, there is always going to be noise around it – and to that end the company has recently agreed to pay more than US$200m to settle a shareholder class action from the failed Zillow Offers iBuying experiment, which was an attempt to move beyond being a property marketplace and buy and sell homes itself. The model ultimately failed, and they were forced to take large write downs. While this part of the ZG history is now in the news, we see it largely as cleaning up an old mistake rather than anything reflective of their future earnings potential.
After a very challenging period for the property platform, the stock is now materially lower and expectations have reset, making the valuation far more compelling. UBS are buy rated with a $48 price target and we agree with their analysis. We don’t believe we need a booming US housing market for the thesis to work — simply stabilising activity, continued growth in Rentals and management delivering the expected operating leverage should lead to a meaningful re-rate higher.
- We don’t currently own Zillow, but around US$30 we think it has become cheap enough to seriously reconsider.
MM is now bullish ZG US ~$30
Add To Hit List